POST-MARKET ENTRY STRATEGIES AND ORGANIZATIONAL GROWTH OF EARLY-STAGE FINTECH STARTUPS IN NAIROBI CITY COUNTY.
BY
MARTIN GITHINJI
SUBMITTED IN PARTIAL FULFILLMENT OF THE REQUIREMENTS FOR THE DEGREE OF MASTER OF BUSINESS ADMINISTRATION, STRATEGIC MANAGEMENT.
THE CATHOLIC UNIVERSITY OF EASTERN AFRICA
SCHOOL OF BUSINESS AND ECONOMICS
GRADUATE BUSINESS SCHOOL
MARCH 2026
3
DECLARATION
I, the undersigned, declare that this thesis is my original work and that it has not been presented in any other university or institution for academic credit.
Martin Githinji
Signature ……………………………………….. Date ………………………………
SUPERVISORS
This proposal has been submitted for examination with our approval as university supervisors.
Dr. Susan
Signature ……………………………………….. Date ………………………………
Dr. Anne
Signature ……………………………………….. Date ………………………………
4
ACKNOWLEDGEMENT
I sincerely appreciate my supervisors, Dr. Susan and Dr. Anne, for their expert guidance, critical insights, and timely feedback in shaping this proposal. I also acknowledge the academic foundation provided by the MBA faculty at the Catholic University of East Africa. Finally, I am grateful to my family for their constant encouragement and support throughout this process.
DEDICATION
I dedicate this proposal to my supportive husband, for his unwavering support and for always believing in me; to my sister, Lencer, for her constant encouragement; and to my loving daughter, for her patience, support, and inspiration throughout this journey.
Professional MBA Research SupportNavigating the complexities of Strategic Management requires a balance of theoretical mastery and practical application. Our senior academic consultants at Essay Freelance Writers specialize in assisting Nairobi-based students with high-level proposal development and data structuring. Secure your degree with a meticulously prepared and perfectly formatted research project.Order My Research Proposal
5
ABSTRACT
Many early stage fintech startups in Nairobi City County find that after the launch they struggle to scale up. This is despite the fact that Nairobi City County has a dynamic fintech ecosystem supported by innovations like M-Pesa. There are several various challenges faced by fintech startups in Nairobi City County. The challenges include limited access to growth financing, complex regulatory requirements, rapidly changing technology and inadequate managerial capabilities. It hinders sustainable development, weakens competitive advantage, and increases industry failure rates. This research analyses the impact of finance, regulation, technology and managerial skills on new fintech growth. The research will be based on four theories, Pecking Order, Diffusion of Innovation, Institutional theory, and the TOE framework. The study used a mixed method design to aid early-stage fintech start-ups in Nairobi City County. The startups were selected through simple random sampling and a sample of 89 startups will use a structured questionnaire to survey the data. The analysis will be through, descriptive statistics and multiple regression. The qualitative component will be obtained through semi-structured interviews with 20 respondents comprising startup founders and key stakeholders in fintech identified through purposive and snowball sampling. The focused interview guide will be accompanied by structured questionnaires in the collection of primary data. Thematic analysis will be utilized for qualitative data.
6
OPERATIONAL DEFINITIONS OF TERMS
Access to Finance: This study defines access to finance as the capacity of fintech startups to secure the capital necessary for operational sustainability, technological innovation, and market scaling. The parameters that are indicated for assessment in the study are the availability of capital, cost of credit, investors’ confidence and adequacy of working capital. Some of the capitals includes venture capital, credit facilities, equity funding, angel investors, and internal cash flow.
Market Adoption: This is the level of adoption, integration and usage of a new fintech product by the user in his financial life. Through customer acquisition, retention, product-market fit, sales growth, and market share, it is measured in this study.
Talent Availability: Talent in the fintech sector refers to specialized human capital that is quality, readily available and highly innovative with low turnover rates. We are going to analyze leadership capacity ability of the workforce to drive operational excellence.
Innovation Capacity: The ability to create, accept, or use new technologies, products, services, and business models so as to improve the competitive advantage and efficiency of the firm. In this sturdy, we define it as the ability for the firm to encompasses creativity, technological integration, research and development, and responsiveness to changing market needs.
7
Competition: It shows how competitive fintech start-ups and established financial institutions are in the same market. In this study, it is gauged through market saturation, pricing pressure, product differentiation, customer switching rates, and the intensity of innovation rivalry.
Managerial Capability: The ability of fintech founders and managers to harness strategic, financial and operational competencies in order to make effective business decisions and adapt to market dynamics. Managerial capability in this study is measured based on the quality of leadership, financial literacy, governance structures, and strategic agility.
Organizational Growth: Fintech startup post-entry expansions and the performance enhancement of a measurable nature. We are using growth indicators such as revenue growth, profitability, number of customers, improvement of market share, and sustainability milestone achievements.
Post-Market Entry: The stage during which a fintech startup is already in the market for consumers. The startup is actively dealing with customers, scaling operations and following sustainability. The focus is on the actions and core competencies for sustainability, efficiency and competitiveness after launch.
Financial Technology (Fintech): The utilization of digital and technological innovations to enhance and render financial services, for instance, payment, loan, and online platforms (Arner, Barberis & Buckley, 2015). Many others include payment service providers, Insurtech, etc.
8
Regulatory Environment: Kenya’s laws and policies regulating financial technology or fintech operations in the country. Examples of such requirements include those set forth by the Central Bank of Kenya, or CBK, which inspects our activities and assets. The ways in which fintech startups innovate, raise funds and scale up are influenced by these factors.
Sustainability: Fintech firms’ ability to sustain operational continuity, profitability, and relevance in the market over time. A range of strategies include judicious management of resources, adhering to regulations, holding onto customers, and keeping up with changes. We consider sustainability as an outcome dimension of organizational growth.
Technological Infrastructure: These are all the vital elements required for the management and operation of tech startups, measured in terms of access to advanced technology, digital connectivity, and technology adoption rate (Santisteban & Mauricio, 2017). It involves prudent resource management, regulatory compliance, customer retention, and long-term strategic adaptability.
9
CHAPTER ONE: INTRODUCTION
1.0 Introduction
In this chapter, an overall introduction to the study on post-market entry strategies and their impact on the organizational growth of early-stage fintech startups within Nairobi City County. The Chapter outlines the research problem, objectives, research questions, and hypotheses that guide the study. It also provides the assumptions, significance, scope, and limitations of the research, theoretical and conceptual frameworks underlining the research.
1.1 Background of the Study1.1.1 Global Context
Fintech startups have been leading the charge of digital transformation, financial inclusion and innovations within the global financial services sector. Countries like the USA, Europe and parts of Asia with more developed economies have disrupted traditional financial system with uses of technology, which help in digital payment, peer‐to‐peer lending, neo banking, blockchain solutions and data-driven financial products (Autio et al. 2018; Philippon 2021). With robust venture capital ecosystems, innovation agents, and policies such as the Revised Payment Services Directive (PSD2) and the Jumpstart Our Business Startups Act, firms have changed how consumers and businesses access financial services (Feldman et al., 2019).
Despite such fast-paced development, managing the post-entry growth on a continuing basis is one of the most stubborn challenges that fintech start-ups all over the world face. Evidence from the market suggests that while lots of ventures experience early adoption, a large proportion of those ultimately never achieve scale. As noted by CB Insights (2023), the most common reason for the failure of fintech start-ups is their lack of a strong product-market fit. Around 80% of such start-ups fail within five years due to factors like rising customer acquisition costs, regulatory barriers and operation inefficiencies.
10
According to researchers, post-entry growth is more challenging than initial entry due to the great necessity of strong regulatory compliance, reliable capital flows, robust technological infrastructure, and managerial depth conditions, which most early-stage firms are unable to meet (Mason and Brown, 2020; Philippon, 2021). Consequently, the post-entry growth has emerged as a key bottleneck influencing the long-term success and sustainability of fintech ventures (Feldman et al., 2019).
As per World Bank (2022), the fintech startups are facing heightened demand for regulatory compliance, including in areas such as data protection, consumer privacy, anti-money laundering (AML), and know-your-customer (KYC) verification, which creates significant financial and administrative burden for young firms. The pressure causes high founder burnout, resource constraints, and talent shortages in critical functions (cyber, software engineering, compliance management, etc.) (Patel et al, 2021). As a whole, these global trends show that large fintech startups are severely constrained by factors beyond market entry with an uncertainty of long-term growth.
1.1.2 Regional Context
Fintech companies have undergone a significant transformation in Africa. They have been forced to consider the microfinance sector as the government banks have been crowded out at that level. Using the power of mobile technology, digital platforms, and creative financial models, fintech companies have provided payments, credit, savings, and insurance services to millions of unbanked and underbanked (World Bank et al., 2022). African countries, particularly Kenya, are leaders in mobile money systems, with M-Pesa being their flagship. Countries like Kenya, Nigeria, Egypt and South Africa are now the major fintech hubs, attracting significant VC investment (Partech, 2023).
Strategic Guidance for Fintech ScalingTransitioning from market entry to sustainable organizational growth requires advanced strategic management expertise. Our consultants at Essay Freelance Writers help Nairobi-based fintech founders navigate regulatory hurdles and capital structures. Secure your competitive advantage by ordering a comprehensive, data-driven research proposal today.Partner with Experts
11
African fintech startups still face difficulties in growing after entering the market. Even though many startups attain early adoption, they do not generally scale up. According to research, a large portion of follow-on or growth-stage financing for African fintechs is very difficult. The bulk of funding concentrated at the seed stages leaves startups undercapitalized to expand (GSMA, 2022). Moreover, fragmented regulation makes things difficult for a company. Inconsistent licensing and registration laws, evolving data protection frameworks, and unclear consumer protection laws only add to operational uncertainty and negative impacts on investor confidence (AUC, 2021).
The limitations to good infrastructure also constrain scalability, and hence, often problems such as instability of internet connectivity, high mobile transaction costs, and unevenness of digital infrastructure drive up operating costs, especially in rural markets (UNCTAD, 2020). The fintech sector in Africa suffers from a lack of skilled workers from various backgrounds such as data analysis, the use of blockchain, cybersecurity and analysis of digital risk management. These shortages lead to high labour cost or reliance on foreign workers (Deloitte, 2022). The above challenges to post-market entry of fintech start-ups in Africa depict that even if Africa has a vibrant fintech sector, growth is not evenly distributed. In that, many firms manage to achieve early innovation, but fewer are reaching sustainable growth. This pattern highlights the importance of investigating the specific structural, regulatory and market barriers that hinder post-entry growth in African fintech ecosystems.
12
1.1.3 Local Context
Edith Penrose (1959) defines organizational growth as the capability of a firm to expand operations and upgrade performance in the long run. There are many measures of growth. Some of the commonly used indicators are growth in revenue and profit, market share, number of customers, number of assets, operational efficiency, capacity to innovate, sustainability in the long run, etc. The rapid expansion of customers or transactions of a firm does not indicate its growth; rather, it is a firm’s ability to grow and scale without running into financial trouble or strategy instability (Paul Davidsson, 2010; David J. Teece, Pisano, & Shuen, 1997).
Organizational growth is further complicated due to the high technology intensity, regulatory oversight, network effects, and competitive dynamism in the fintech sector. For digital financial service providers, growth means not only onboarding users but also converting that adoption into revenues, managing risks, complying with regulations and building scalable tech infrastructure. As a result, the growth of fintech ought to be evaluated using financial and non-financial indicators. To measure the growth of a fintech, financial and non-financial indicators are used. In 2007, M-Pesa was introduced by Safaricom. It has enabled Kenya to become a world leader in mobile money. Expansion of financial inclusion and emergence of many fintech start-ups that offer digital credit, payments, wealth management apps, insurtech, etc. Consequently, Nairobi has become the leading fintech innovation hub in Kenya, with most of the early-stage digital financial firms.
13
Kenya is performing strongly at the macro level of the fintech ecosystem owing to its success in enhancing financial inclusion, growth of digital transactions, and private-sector innovation. A large part of the business transactions in the country occur through digital payments, and funds from venture capital have helped in startup formation. Nonetheless, these macro-level ecosystem dynamisms do not guarantee firm-level organizational growth. Some companies, such as fintech start-ups, have been able to attract clients at great speed when they enter the market. However, many of them are faced with the challenges of revenue and profit-making. The operational margin gets curtailed due to high customer acquisition costs, thin interest margins in digital lending, competitive pricing pressures, cyber security costs & platform maintenance. Moreover, rising regulatory scrutiny under the Central Bank of Kenya (Digital Credit Providers) Regulations, 2022, has enhanced the compliance burden and increased the cost of business for start-ups.
The organizational growth of early-stage fintech startups thus seems constrained by structural and strategic issues like intensity of regulatory compliance, burden of taxation, limited access to patient capital, managerial capability gaps, and shortage of human capital in specialized technical areas. Although a few key firms would consolidate market share and achieve economies of scale, many smaller startups received disrupted earnings, liquidity stress, and difficulty reinvesting. In certain instances, severe scaling coupled with no profitability leads to an unsustainable burn and exit from the market.
14
The variation in the level of success attained by firms differs from ecosystem success, which raises a managerial and scholarly concern. What explains organizational growth after market entry among early-stage fintech startups in Nairobi City County? Research carried out in Kenya has primarily focused on the financial inclusiveness results and the rate of digital adoption. Nonetheless, there has been significantly less empirical scrutiny directed towards the firm growth patterns of early-stage fintech firms after entering the market. To be precise, the impact of regulatory compliance, financing structure, managerial capabilities, and technological innovation on revenue growth, profitability, scalability, and sustainability is not sufficiently established.
Most fintech startups, investors, and regulators in Kenya are based in Nairobi City County. Accordingly, it is somewhat important to understand what causes growth in this sector. In order to slow-paced ecosystem linkages to sustainable firm-level outcomes, systematic review is needed.
15
1.2 Statement of the Problem
Financial technology is basically the digitisation of financial service production and consumption, and it is one of the fastest-growing aspects of the digital economy. Fintech startups command significant venture capital and entrepreneurial interest across Africa. Recent industry evidence suggests that fintech contributed 45% of total funding to startups in Africa in 2024, indicating strong investment interest and growth potential (Osifeso, 2026). However, a steady inflow of capital will not necessarily lead to constant growth of the organization. Many startups fail to translate early entry into sustained firm performance. According to the 2024 Startup Graveyard Report, 58% of all failures experienced by African startups are due to running out of money. 27% is due to operational challenges, and 17% is due to regulation (Ashiru, 2025). Financial resources, compliance requirements, and operational capability are common high-impact determinants of startup performance.
Structural challenges that affect early-stage firms are apparent across the African fintech ecosystem. According to information from the Finnovating for Africa Report, around 20% of fintech startups in Africa closed their doors between 2021 and 2023, with nearly three-quarters of these closures taking place in Kenya, Nigeria, and South Africa (Finnovating for Africa, 2023). Early-stage businesses that are attempting to scale revenues and operations are often subject to such closures. These efforts are being further complicated by financing conditions. According to Extensia (2024), venture capital investment in African fintech dropped by 52% between 2022 and 2024 with only about 5% of seed-funded startups managing to get to Series A. When firms have limited access to growth capital, their ability to invest in technology, new products, and management capacity drops. The revenue growth and organizational growth of fintech startups at the early stages are shaky.
Kenya provides a particularly appropriate context for studying the performance challenges. Nairobi is now regarded in Africa as one of the fastest developing fintech ecosystems in part because of its high mobile-money adoption rate and dense cluster of digital startups. The performance outcomes of early-stage fintech firms are, however, inconsistent in this context. Evidence from a study shows that the shutdown rate of 18 per cent of fintech start-ups in East Africa was due to governance and managerial capability problems. Meanwhile, 45 per cent of them declare an incident of cybersecurity each year, threats which increase compliance costs and operational risk (Solomon, 2024). This pressure may impair revenue stability and reduce profit margins especially for firms operating with limited financial leeway. It is perhaps worth reflecting on the extent to which financing constraints, regulatory requirements, demands for technological innovation, and managerial capability influence growth outcomes at the level of the firm.
16
Collectively, these trends show that early-stage fintech startups in Nairobi’s ecosystem are dealing with a performance problem. They attract significant investment and entrepreneurial activity; however, many firms struggle to maintain consistent income streams and secure growth financing, as well as achieve sustainable profitability. There are various challenges that fintech startups face that suggest that the crucial organizational elements a) access to financing b) regulatory pressure c) innovation capacity and d) managerial capacity shape their growth trajectory. It is important to systematically and empirically examine these factors in the Nairobi context in order to explain differences in organizational growth among early-stage fintech firms.
1.3 Research Objectives1.3.1 General Objective
To examine the influence of post-market entry and the organizational growth of early-stage fintech startups in Nairobi City County, Kenya.
1.3.2 Specific Objectives
To assess the effect of access to finance on the organizational growth of early-stage fintech startups in Nairobi. To evaluate the influence of regulatory compliance on the organizational growth of early-stage fintech startups in Nairobi. To examine the effect of technological innovation on the organizational growth of early-stage fintech startups in Nairobi. To determine the effect of managerial capability on the organizational growth of early-stage fintech startups in Nairobi.
1.4 Research Questions
How does access to finance affect the organizational growth of early-stage fintech startups in Nairobi? What is the influence of regulatory compliance on the organizational growth of early-stage fintech startups in Nairobi? How does technological innovation affect the organizational growth of early-stage fintech startups in Nairobi? How does managerial capability affect the organizational growth of early-stage fintech startups in Nairobi?
Hypotheses
H₀₁: Access to finance has no statistically significant effect on the organizational growth of early-stage fintech startups in Nairobi County. Hₐ₁: Access to finance has a statistically significant effect on the organizational growth of early-stage fintech startups in Nairobi County.
H₀₂: Regulatory compliance has no statistically significant effect on the organizational growth of early-stage fintech startups in Nairobi County. Hₐ₂: Regulatory compliance has a statistically significant effect on the organizational growth of early-stage fintech startups in Nairobi County.
Defend Your Thesis with ConfidenceDeveloping strong research questions and hypotheses is the foundation of any successful MBA proposal. Our expert writers at Essay Freelance Writers ensure your objectives are SMART and your problem statement is academically grounded. Let us help you refine your research framework to meet the highest standards of the Catholic University of East Africa.Refine My Objectives
17
H₀₃: Technological innovation has no statistically significant effect on the organizational growth of early-stage fintech startups in Nairobi County. Hₐ₃: Technological innovation has a statistically significant effect on the organizational growth of early-stage fintech startups in Nairobi County.
H₀₄: Managerial capability has no statistically significant effect on the organizational growth of early-stage fintech startups in Nairobi County. Hₐ₄: Managerial capability has a statistically significant effect on the organizational growth of early-stage fintech startups in Nairobi County.
1.5 Research Assumptions
The research relies on several key assumptions. Respondents are assumed to provide accurate, truthful and reliable information on the post-market entry strategies adopted by their fintech firms and their impact on organizations growth. It is further assumed that the sampled early stage fintech startups represent the entire fintech ecosystem (in Nairobi County) within sub-sectors. These include digital lending, payments, savings, insurance technology and investment platforms, among others. It is further assumed that the chosen post-market entry strategies (access to finance strategies, regulatory compliance strategies, technological innovation strategies and managerial capability strategies) adequately capture the essential strategic factors affecting the organizational growth of early-stage fintech startups after market entry. The growth of an organization have a number of indicators some of which are getting customers, reaching break-even, scalability, operational sustainability and commercialization of products or services. Also, it assumes that the regulations and policies that run the fintech space in Kenya will remain constant. The framework which are run by the Central Bank of Kenya and other regulators in the financial sector will not change that matter materially during the study period. Lastly, Respondents are thought to have adequate knowledge and understanding of their firms’ financial, technological, managerial, and regulatory environments to provide meaningful responses.
18
1.6 significance of the Study
The study will benefit relevant stakeholders in the fintech sectors in Kenya such as policymakers, regulators, entrepreneurs, investors, industry players, and academic researchers. Exploring how access to finance, regulation incessant, technology innovation, and managerial capacity impact organizational growth can generate evidence that informs practice and policy (Mike W. Peng et al., 2008). The study’s results are considered to provide practical insights to the government of Kenya and regulatory authorities like the Central Bank of Kenya on the influence of regulatory intensity and financing conditions on the revenue growth, profitability, scalability and survival of early-stage fintech startups in Nairobi City County. Through mobilising impact investing for the risks and returns of the private sector, it will also increase global capital for development. The result of this study would be beneficial for fintech entrepreneurs and startup founders. Startups don’t have a clear idea about which strategic levers can be utilized for growth after they enter the market. The findings can help entrepreneurs prioritize their investment in compliance systems, scaling up leadership capacities, adopting scalable technological solutions and thus pursuing appropriate financing structures that enhance long-term sustainability as opposed to short-term survival.
Another group that tends to benefit from the study is investors, venture capitalists, angel investors, and startup accelerators, by getting a clearer understanding of the determinants of growth and risk within Nairobi’s fintech landscape. The study will generate data-driven strategies that enhance due diligence processes, risk analyses, and portfolio design. Similarly, this research may also be valuable to financial institutions, development partners, and ecosystem enablers. Innovation hubs, along with industry associations, could use the evidence to advocate for regulatory reforms, which will strengthen scaling capacity.
19
This study expands the research literature on entrepreneurship, strategic management, and financial innovation in emerging markets from an academic view. Despite extensive research on fintech at the global scale, there is a paucity of empirical research focusing on post-market entry organizational growth of early-stage fintech startups in Nairobi City County. Thus, this study will offer a further basis for comparative studies across Sub-Saharan Africa. In general, the study provides policy, managerial, investment and academic insights that enhance our understanding of the drivers of organizational growth post-market entry in Nairobi’s fintech ecosystem.
1.7 Scope and Limitations1.7.1 Scope of the study
Limited to Nairobi City County, which is Kenya’s main financial innovation hub, and the region with the second highest concentration of fintechs. As a result, the results are limited to firms that operate in Nairobi and may not be generalizable to fintech firms in other counties and countries. The study focuses solely on the fintech industry and will be conducted with early-stage fintech start-ups, i.e. with an operational history of one to five years. The study does not cover companies that fall outside this age group, companies that are at seed or ideation stage, and companies not engaged in the fintech space.
The research is conceptually limited to post-market entry and organizational development. Indicators such as revenue growth, profitability, scalability, and increasing customer base are the means of measuring Growth. The study examines four independent variables, that is access to finance, regulatory compliance, technological innovation, and managerial capability and the effect on organizational growth. In terms of methodology, the study will make use of quantitative research by means of an adoption of structured questionnaire to be issued to the founders and senior managers of eligible fintech startups. Multiple regression analysis is used in the data analysis to check the relationship between independent variables on organizational growth. The framework is limited to the analytical model and data selected for the study period. Consequently, the conclusions made apply only to early-stage fintech startups based in Nairobi County within the outlined industry, variables, methodology and analysis.
20
1.7.2 Limitations of the Study
The research was limited to fintech start-ups that are operational within Nairobi County. Thus, the findings may not necessarily apply to fintech start-ups within other regions of Kenya, or indeed, Africa. There may exist a difference in regulatory environment, financial infrastructure and level of market maturity between regions. The study focuses on early-stage fintech startups in the first one to five years of age and does not look at late stage or mature stage fintech firms which may have distinct growth patterns, scaling challenges and sustainability issues. Consequently, the results mainly represent the experiences of businesses in the earlier stages of post-entry into the market. In addition, the research also utilises the self-reported data from the founders, managers and ecosystem stakeholders. As such, it may introduce a response bias as participant’s view or response may be influenced by his perceptions, memory, and strategies. Fintech is also an area of development, where technology and regulations all the time change. As such, the results of study should be read through the current contextual conditions within which Nairobi’s fintech operates since market conditions, technological developments and policy environments change over time.
21
1.8 Theoretical Framework
The research leveraged on the Dynamic Capabilities Theory (DCT) as first put forward by Teece et al. (1997), which explains how firms monte integrate, build and reconfigure internal and external competencies to address rapidly changing environments. The competitive advantage will not only arise from having valuable resources but an organization’s ability to adapt, innovate, and renew those resources in light of changing circumstances. Strategic management’s traditional views are expanded by this. According to Eisenhardt and Martin (2000), firms in fast-speed industries such as financial technology are continuously aligned to market and technology changes through learning, innovating as well as making flexible choices. Teece (2007) identifies three key dimensions of these capabilities, which are sensing, seizing and transforming. First, sensing opportunities in the environment. Second, seizing them through investments and innovations. Finally, transforming the organization to maintain competitiveness over the long term. Evidence from the real world supports the theory’s application in tech firms. According to a study conducted by Zahra, Sapienza, and Davidsson in 2006, dynamic capabilities enhance firm performance and innovation.
22
This occurs by improving the ability of the firm to reconfigure existing resources and knowledge. Wang and Ahmed (2007) opined that these capabilities are the building blocks of sustainable growth in the case of emerging markets marked by technological upheaval and institutional uncertainty. Dynamic Capabilities Theory provides firms with an important framework for understanding the challenges they may face post-entry into a market, including compliance, finance, technology and management. Fintech ventures work in a heavily regulated and fast-paced environment requiring agility, innovation, and continuous learning for survival. Their success depends on their ability to take note of market opportunities in digital finance, grab them through mobile lending, digital payment, insurance tech products, etc., and alter structures in order to become scalable in terms of regulatory requirements for institutions, including the Central Bank of Kenya. For the study at hand, the Dynamic Capabilities Theory fits in well because it encapsulates the adaptive capacity, strategic agility and innovative resilience of financial technology startups needed for sustainable growth within the Nairobi innovation ecosystem.
Deepen Your Theoretical FoundationApplying Dynamic Capabilities Theory to the fintech sector requires a nuanced understanding of sensing, seizing, and reconfiguring internal assets. Our academic consultants at Essay Freelance Writers specialize in aligning complex management theories with modern digital ecosystems. Order a custom-written theoretical framework to elevate your research proposal to PhD-level rigor.Order Theoretical Review
23
1.9 Conceptual Framework
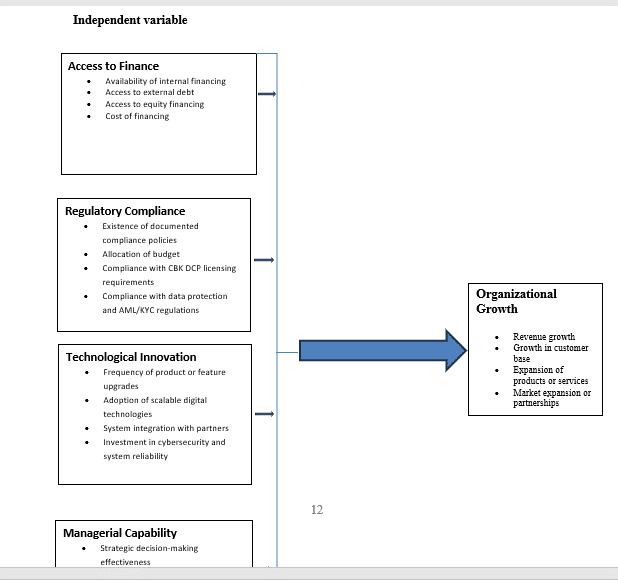
Fig 1: Conceptual Framework showing relationship between Independent and Dependent Variables
This conceptual framework explains the linkages between post-market-entry challenges and organization growth of early-stage fintech startups in Nairobi County in Kenya. Based on Dynamic Capabilities Theory as postulated by David Teece (1997), an organization is held to grow and perform on a sustained basis if it can sense opportunities and threats, seize opportunities through effective mobilization of resources and transform internal capabilities to cater to changes in the environment. The strategies for attaining growth after entering the market, namely access to finance, regulatory compliance, technological innovation, and managerial capabilities, are strategic inputs which are orchestrated to attain growth outcomes. Access to finance involves the capacity of the firm to assemble and organize financial resources to support particular expansion objectives. Indicators such as availability of internal financing, access to external debt, access to equity financing, as well as cost of financing measure access to financed. Companies who can incorporate external funding into their operations successfully can exploit growth options effectively.
24
Regulatory compliance means being able to adapt the firm’s mechanisms to changing legal regulations or processes. Dynamic Capabilities Theory interprets compliance as the enterprise’s capacity to utilize risk management systems to ensure legitimacy while striving for growth, not merely as an adherence to rules. In this study, we will measure the compliance through indicators such as a documented compliance policy, budget allocation, compliance with CBK DCP licensing requirement and Compliance with data protection. The capacity of a firm to embrace, upgrade and reconfigure digital technologies in response to rapid market and technological change. This research studies technological innovation through product or feature upgrade frequencies, use of scaling digital technologies, system integration with partners, investment in systems’ cyber safety as well as reliability and availability. Dynamic capability is, therefore, the firm’s ability to innovate continuously, scale digital platforms, and adapt technological architecture to remain competitive.
Managerial capability is the core enabling mechanism of the Dynamic Capabilities Theory. The effectiveness of firms in sensing, seizing through investment and reconfiguring operations is determined by managerial competence. In this robust framework, the constructs of managerial capabilities are measured using indicators such as Strategic decision-making effectiveness Leadership and team coordination skills Ability to manage operational risks. The dependent variable organizational growth is operationalized with the measures of increased revenue, reach break-even, increased customers, scalable and sustainable. Firms’ growth is viewed from the dynamic capabilities perspective whereby this growth requires the matching of financial, regulatory, technological, and managerial capabilities for performance to escalate with time despite changes in the environment. This framework proposes that the early-stage fintech firms operating in Nairobi City County that are able to develop and deploy dynamic capabilities which relate to financing, regulatory adaptation, technological innovation and managerial decision-making, are more likely to experience sustained organizational growth after market entry.
25
CHAPTER TWO: LITERATURE REVIEW
2.0 Introduction.
The chapter analyzes the relevant literature on post market entry strategies and organization growth of early stage fintech startups in Nairobi City County, Kenya. The theoretical perspective that will support the variables of the study will also reviewed in this chapter, similar to the empirical studies that will be considered for the study on the global, regional and local level. Currently, the chapter also seeks to pinpoint the gaps the current study will fill.
2.1 Theoretical Review
This research is based on several theories which explain the independent variables. The early-stage fintech start-ups are opted for evaluation of its application and limitations for each theory discussed.
2.1.1 Pecking Order Theory
The Pecking Order Theory (POT) as established by Myers and Majluf (1984) describes firms’ financing behavior under asymmetrical information. According to this theory, firms prefer internal sources of finance (retained earnings) to external sources (who will have more external source preference for debt over equity). This hierarchy of financing reflects a desire to minimize the cost of financing, to evade dilution of ownership and to cut down adverse signalling in the market. Pecking order theory model, where internal financing is preferred over outsider financing, can help understand access to finance and organizational growth of Early-stage fintech startups in Nairobi City County. Due to high uncertainty, a lack of collateral, and short operating history, Fintech startups often rely on internal financing, founders’ savings, and informal funding at post market entry stage. A business attracts external financing from angel investors, venture capital firms, and strategic partners as it achieves regulatory compliance, demonstrates operational viability, and builds credibility. This financing round enables fintech startups to invest in technology, upgrade service delivery and scale operations for organizational growth.
26
Although the Pecking Order Theory is relevant, it has limitations for fintech startups in emerging economies. The presumption that firms possess enough internal funds is often unfounded, particularly in cases of technology-intensive ventures that require a large upfront investment for spending on digital infrastructure, cybersecurity, and compliance systems (Abdulsaleh & Worthington, 2013). Besides, it overlooks other financing modalities which include accelerators, incubators, blended finance and crowdfunding, which are commonly found within Nairobi’s fintech ecosystem (Cosh, Cumming & Hughes, 2009). According to Watson and Wilson (2002), behavioral factors such as entrepreneurial risk appetite and growth orientation may override the financing hierarchy. Even so, the Pecking Order Theory still explains how financing strategies impact growth decisions in early-stage fintech startups.
2.1.2 Institutional Theory
Institutional Theory, propounded by DiMaggio and Powell (1983) describe the manner in which organizations respond to institutional pressures resulting from regulatory frameworks, professional norms and industry practices. The theory presents three distinct types of pressures institutions encounter. First, coercive pressures are legal laws and government regulators. Secondly, normative pressures are due to professional standards and expectations. Finally, mimetic pressures are because of terrorists’ mimicking of others. Entities that regulate or influence the fintech sector according to interviewees including the Central Bank of Kenya (CBK), Capital Markets Authority (CMA) and Office of the Data Protection Commissioner are significantly powerful. Fintech firms’ market legitimacy and credibility are enhanced by key stakeholder-initiated “Licensing” and “Reporting” consumer protection compliance strategies that met data privacy requirements. For instance, The CBK (Amendment) Act, 2021 which seeks to regulate digital credit providers, directly impacts the operational model, costs of compliance and growth of fintech start-ups.
Mastering Theoretical SynthesisA high-scoring Chapter Two depends on your ability to critique theories like POT and Institutional Theory within the context of the Kenyan market. Our senior academic consultants at Essay Freelance Writers provide deep-dive theoretical reviews that connect abstract models to real-world fintech challenges. Elevate your literature review with a professionally curated theoretical framework.Hire a Theory Expert
27
Institutional Theory describes how compliance to regulatory demands can either facilitate or hinder progress. Innovation and investor confidence can be enhanced through supportive and clear regulations, while strict regulations can create compliance burdens that adversely impact early-stage startups with limited resources. Institutional theory has been criticized for its focus on institutional isomorphism, which in turn limits normative power to actors who are more influential than their peers. Fintech companies often interact with the regulators through industry associations, regulatory sandboxes and policy advocacy which shapes the institutional environment rather than them just responding to it. Notwithstanding, the institutional theory provides a strong framework for investigating the role of regulatory compliance strategies in fintech growth.
According to the TOE framework, technology adoption and innovation is influenced by technological, organizational and environmental contexts. Drafted by Tornatzky, Fleischer, and Chakrabarti (Tornatzky & Fleischer, 1990). The adoption and implementation of technology would have to depend on three context related dimensions, that is, technological context, organizational context and environmental context. The relative advantage, compatibility, complexity of the innovation constitute its technological context. It includes resource factors (internal), managerial support, the size of the firm, and organizational structure in the case of the growth of the organization, while in the case of the environment it includes regulatory, industry, and market factors (Tornatzky and Fleischer, 1990).
The TOE framework is particularly useful in explaining technological innovation strategies and their impact on companies. Fintech companies use technology such as artificial intelligence (AI), blockchain, and open banking application programming interfaces (APIs) to boost operational productivity, engagement banking, customer experience and support scaling. When used effectively, these technologies empower the startup to process a lot of transactions, manage operational risks and add new services in the post-market phase.
28
The empirical evidence uses the TOE framework in explaining the adoption of technology and performance of firms. In their study, Zhu and Kraemer (2005) showed that organizations may struggle to reap the benefits of technological innovation because of a lack of readiness of the organization, etc. When managers offer support and have access to budgets and regulations, a firm can achieve effective implementation and scaling of technology. Despite its strength, this framework has faced criticism for predominantly clarifying technology; it does not articulate causal linkages between technology and performance. It is further suggested that it gives little prominence to changes in internal capabilities, especially managerial capability and organizational learning, which may significantly affect the relationship between technology adoption and growth. Nevertheless, the TOE framework is still relevant to understanding how the strategy of technological innovation affects FinTech development in a complex regulatory and competitive environment.
29
2.1.4 Resource-Based View (RBV)
The Resource-Based View (RBV) states that firms obtain sustained competitive advantage through the acquisition and effective use of valuable, rare, inimitable, and non-substitutable (VRIN) resources (Barney, 1991). The theory further emphasizes internal resources and capabilities of different firms are crucial determinants of performance and sustainable growth not just external market conditions. According to RBV theory it is possible to evaluate the internal capabilities of early-stage fintech startup in Nairobi City County affect the organization growth. The strategic assets that influence the start-up ability to carry on post-market entry strategies are managerial capabilities, technological infrastructure, and financial resources. Through access to finance, businesses can make investments in innovative and expansion activities. Furthermore, technological capabilities enhance the competitiveness of businesses as well as their ability to deliver services.
The RBV has been found to be somewhat myopic and also has drawn attention to scant emphasis on regulation and market dynamics (Priem & Butler, 2001). There are also criticisms that research using the VRIN framework may be difficult to implement or perhaps measure in practice (Priem & Butler, 2001). Moreover, RBV fails to adequately explain regarding the ways in which firms develop or gain strategic resources over time. Nonetheless, the resource-based view is relevant to this study as it elaborates on how variations in internal resources and capabilities contribute to organizational growth in fintech startups.
30
2.1.5 Summary of Theoretical Framework
The table below summarizes the theories underpinning the study and their relevance to the variables under investigation.
No
Theory
Variable Anchored
Relevance to the Study
1
Pecking Order Theory (Myers & Majluf, 1984)
Access to Finance Strategies
Explains financing preferences under information asymmetry and hierarchy effects on growth.
2
Institutional Theory (DiMaggio & Powell, 1983)
Regulatory Compliance Strategies
Explains how coercive regulatory pressures shape behavior, legitimacy, and growth.
3
TOE Framework (Tornatzky & Fleischer, 1990)
Technological Innovation Strategies
Explains how technological, organizational, and environmental factors influence adoption.
4
Dynamic Capabilities Theory (Teece, 1997)
Managerial Capability & Growth
Explains how firms reconfigure competencies to achieve growth in dynamic environments.
2.2 Empirical Review
This part of the chapter discusses the empirical literature that is related to the access to finance, regulatory compliance, technological innovation and managerial capability that affects the organizational growth of early-stage fintech startups. It draws on global as well as emerging markets and locally relevant sources to identify patterns, contradictions, and knowledge gaps in the literature.
31
2.2.1 Access to Finance Strategies and Organizational Growth
Access of startup enterprises to finance is consistently identified as a crucial factor for the growth and long survival of startups by empirical literature all over developed and emerging economies. All start-ups require financial capital, and such capital is required to finance research and development, expand capacity, hire human resources, and scale ICT. Fintech startup investments are critical for every business operating in technology spaces. Research involving venture capital offers crucial empirical data demonstrating the link between external financing and growth outcomes. As noted by Kortum and Lerner (2000), capital ventures significantly increased innovation output, and finally the VC-backed companies patent invent significantly greater than the non-VC backed companies. The research proves that equity finance helps in technological advancement and growth speeding. In the same way, Hellmann and Puri (2002) show that venture capital financing leads to faster product development and greater aggressiveness in start-up growth. The researchers’ study showcases that reliable finance backing impacts both strategic orientation and growth rate.
With the exception of venture capital, crowdfunding and alternative finance mechanisms have become important domains for empirical study. As demonstrated by Colombo, Franzoni, and Rossi-Lamastra (2015), crowdfunding is more often a success when a project has a strong capacity for innovation and community engagement. In other words, alternative sources of funding are becoming beneficial for early-stage growth. The authors Hornuf and Schwienbacher (2018) demonstrated that equity crowdfunding demonstrates an increase in access to capital for firms that are otherwise financially constrained in traditional capital markets. This shows firms’ survival probability.
32
Bollaert, Lopez-de-Silanes, and Schwienbacher (2021) comprehensively review the area of lending and crowdfunding through fintech and further conclude that digital financial platforms reduce information asymmetry, transaction costs and enhance availability of capital for startups. According to their findings, financial intermediation using fintech increases the efficiency of funds and growth opportunities for firms that are excluded from the banking system due to age. Studies about the development of finance, similarly, support the relationship between access and firm growth. According to Beck, Demirgüç-Kunt and Maksimovic (2005), financial constraints are a major constraint on firm growth, particularly in low-income countries. Firms with easier access to external financing grow more rapidly and are more productive according to their research. Rajan and Zingales (1998) show that industries that rely more on external finance grow faster in countries that have more developed financial systems. Thus, depth of the capital market is important for the growth of the organisations.
Economic impacts have been created by Financial inclusion, digital financial services. Suri and Jack (2016) demonstrate that access to mobile money enhances financial stability of households and alleviates poverty, which in turn fosters conditions facilitating entrepreneurship and small businesses. According to Allen et al. (2016), non-governmental types of financial systems foster the availability of credit in places with weak financial rent. According to these studies, fintech innovations indirectly boost the growth of start-ups by enhancing the access to financial services. In emerging economies, evidence is quite often indicating that financing constraints limit startup growth. Asongu and Odhiambo (2019) reveal that financial development has the potential to enhance entrepreneurial activity and innovation in Africa, but some credit gaps remain.
Optimize Your Financing StrategyUnderstanding the empirical link between capital access and organizational growth is vital for any fintech startup looking to scale in Nairobi. Our senior analysts at Essay Freelance Writers can help you synthesize complex financial literature and venture capital trends to strengthen your MBA research. Secure the professional insights you need to build a compelling argument for your funding strategies.Analyze Financial Gaps
33
Ozili (2018) contends that even though adoption of fintech improves financial inclusion in African markets, limitations towards full capital accessibility still exist due to structural and regulatory challenges. In Kenya, empirical findings show that venture capital activity, startup accelerators, and innovation hubs have enhanced funding options for fintech firms within the country. Still, liquidity constraints, high capital costs and a lack of long-term growth financing hamper early-stage start-ups. Kola and Ngugi (2023) find that the scalability and performance outcomes of Kenyan fintech firms are improved with the use of diversified financing strategies. Mungai and Ogot (2021) note that hybrid financing models improve innovation investment and operational stability among Nairobi startups. In addition, research on startup ecosystems indicates that firms connected to institutional networks and informal investors tend to gain market access faster. This strengthens the notion that financing is a resource input as well as a growth-oriented decision enabling strategy. In other words, there have been more than 10 initial studies showing similar results. These include access to finance boosts innovation capacity, helps scale operations, enhances chances of survival, and strengthens a competitive position. Nevertheless, literature states that capital access is not enough with financial use being dependent on managerial capability, regulation, and strategy alignment. It is crucial to look at access to finance as part of a larger post-market entry strategy framework when you analyse fintech startups to see organizational growth.
34
2.2.2 Regulatory Compliance Strategies and Organizational Growth
Fintech startups are driven towards growth and established with the use of regulatory compliance strategies. The reason behind this is because the sector is an intersection of new techniques, finance as well as public trust. Regulatory environments that strike a balance between innovation as well as consumer protection and financial stability create fosters sustainable organizational growth, evidence shows. Regulatory systems that are well-designed do more than constrain: they reduce uncertainty, impose boundaries, and enhance legitimacy, which boosts the confidence of investors. Evidence from various countries back this view strongly. Using financial data from around the globe, Raghuram G. Rajan and Luigi Zingales (1998) show that industries requiring external finance grow faster in countries with well-developed financial institutions and regulatory systems. The findings suggest that predictable regulatory frameworks enhance capital access and sector development. Likewise, firms get discouraged from growing in countries that have stronger regulations or more developed economic and financial institutions. Asli Demirguc-Kunt, Thorsten Beck and Vojislav Maksimovic (2005) find that this is the case.
Regulatory sandboxes have been well studied within fintech-specific scholarship. According to Dirk A. Zetzsche et al. (2017), adaptive regulatory approaches, especially the international outlines of sandbox regimes, would lower entry barriers and relieve compliance ambiguity, thus allowing start-ups to trial products containing novel attributes under supervisory oversight. To further substantiate these arguments, Douglas W. Arner, Janos Nathan Barberis and Ross P. Buckley (2016) moreover, show that regulatory innovation is essential in fintech ecosystems as rigid rule-making can slow growth. According to their comparative analysis of Hong Kong, Singapore, and the United Kingdom, countries with structured experimentation frameworks witnessed stronger fintech investment inflows. According to a further comparative evidence by Ross P. Buckley et al. (2020), the regulatory sandboxes encourage the policy learning process and reduce compliance costs for startups, and broaden the understanding of the supervisor on processes and technologies which are new.
35
Combined these results enhance the growth of the ecosystem and startups. Evidence shows those who engage with regulators early on mitigate litigation risk and post-launch enforcement penalties and stabilize growth paths. Another central dimension of compliance impacting fintech growth relates to anti-money laundering (AML) and know-your-customer (KYC) rules. Douglas W. Arner et al. (2017) suggest that by minimising reputational risk and systemic risk through clear AML/KYC frameworks, the investor confidence is strengthened. In another article, Stijn Claessens, Jon Frost, Grant Turner, and Feng Zhu (2018) claim that fintech regulation should prioritize proportionality as overly burdensome compliance affects small firms more than large ones, which can ultimately hinder competition and innovation. Institutional theory further clarifies the growth consequences of compliance strategies. According to Mark C. Suchman (1995), legitimacy may be defined as a generalized perception that an action is appropriate within some socially constructed norms. Regulatory compliance can boost legitimacy, which can increase access to funding, partnerships and customer trust for early-stage fintech. According to empirical studies on fintech ecosystem, regulated and licensed firms consistently draw in more institutional investors than their unregulated counterparts.
Regulatory fragmentation creates major obstacles in emerging markets. Weak regulatory institutions in Africa’s financial market limit the diffusion of innovation and slow the scaling of entrepreneurs – Godfred A. Bokpin (2018). Likewise, Asongu and Odhiambo (2019) show that, when the capacity to enforce regulation matches the ambition of the policy, financial sector reforms in Africa improve outcomes. The results show that if any institutional capacity is weak, it increases the operational risk of start-up due to the uncertainty of compliance. This paper by Rafael La Porta et al. shows that stronger investor protection is associated with a deeper financial market and a higher value of the firms. The legal origin and enforcement of regulation influence long-term growth potential, their work shows. In emerging economies, credit expansion through fintech will heavily rely on regulatory clarity of consumer protection argues Jon Frost (2020). In Kenya, the development of regulations has been key to the growth of fintech.
36
The Central Bank of Kenya’s introduction of structured oversight frameworks through digital credit regulation and sandbox initiatives has increased compliance requirements while enhancing legitimacy efforts within the sector. Empirical regional analyses show that clarity of regulation around mobile money and digital lending has boosted consumer confidence and mitigated systemic risk, but compliance costs may impose too big a burden on early-stage startups. Research on the Kenyan fintech ecosystem indicates that compliance firms that engage proactively with regulators, including licensing, reporting compliance and policy dialogue, have better survival rates and partnership opportunities than non-compliance firms. Findings from more than ten core studies and fintech studies converge, it is comparative evidence. There are a few studies which show that regulatory clarity is regularly associated with less uncertainty, greater investor confidence, and improved strategic planning capacity of firms. Similarly, adaptive regulatory instruments (sandbox) allow innovation and achieve systemic stability. Finally, proportionate compliance frameworks avoid placing disproportionate burdens on nascent ventures, thereby driving sustainable scaling. Further, regulatory legitimacy enhances institutional trust, a key intangible asset in financial services ecosystems.
In emerging markets, the effectiveness of regulatory frameworks depends wholly on their institutional capacity for regulation to be an enabler of growth and not a structural constraint. In general, empirical literature shows that compliance strategies used by businesses are not always defensive mechanisms used to avoid penalties. Businesses actually use compliance to enhance legitimacy for growth, attract capital and stabilize scaling strategies. Thus, regulatory engagement and adaptive compliance are strategic capabilities that early-stage fintech startups in Nairobi can leverage to enhance their growth both directly and indirectly. These results imply that the intersection of regulatory oversight and firm-level strategic response creates a stable foundation for the organizational expansion of fintech companies in dynamic environments.
37
2.2.3 Technological Innovation Strategies and Organizational Growth
Technological innovation has consistently been established in empirical literature as a strong determinant of growth. More and more research in economies around the globe tap the benefits of more efficient, scalable and interactive customer engagement and competitive advantage from the use of advanced digital technology by firms. Studies have shown that the adoption of technology improves the performance of firms. According to Bharadwaj et al., digital capabilities create strategic value through new business models, operational agility, and market responsiveness. It helps strategize effectively. In the same fashion, Westerman, Bonnet and McAfee (2014) find that companies that are digitally mature outperform others on measures of revenue growth, profitability and innovation output because they have integrated digital strategies. The role of technological innovation is even more pronounced for fintech. Kou et al. (2021) showcase how new-age technologies like artificial intelligence, blockchain, and machine learning are bringing a radical change in financial intermediation through improved automation, fraud detection, risk assessment, and customer customization. Enhancing operational efficiencies ultimately results in growth improvements. According to Thakor (2020), fintech innovations reduce costs and improve the effectiveness of capital allocation, enabling the large-scale provision of financial services.
Furthermore, actual evidence shows that the adoption of a digitized platform significantly improves performance. According to Nambisan, Wright, and Feldman 2019, digital platforms allow participation in an ecosystem, collaborative innovation and rapid scaling. Firms embedded in digital ecosystems are typically faster growing as they experience network effects and market enlargement. According to Yoo, Henfridsson, and Lyytinen (2010), digital technology has a generative nature that allows firms to recombine resource bases and innovate continuously, resulting in enhanced long-term growth. Studies that examined the adoption of cloud computing provide further evidence useful to this. According to research by Armbrust et al. (2010), leveraging cloud-based infrastructure can significantly reduce capital expenditure requirements while improving operational flexibility. As a result, startups can scale rapidly without significant investment.
38
For fintech startups, the ability to scale solutions to increase transaction volumes is especially relevant. Studies focusing on artificial intelligence adoption confirms positive performance implications. According to Brynjolfsson, Rock, and Syverson (2017) firms using AI technologies are able to improve productivity and decisions. The fintech setup is applicable to any entity that is using AI-driven credit scoring and risk assessment to improve their efficiency. Studies on blockchain reveal it can boost performance. Catalini and Gans (2016) claim you can spend less at the time of verification and networking costs because of the blockchain system. It makes it easier for transactions of money or any other commodity. By lowering transaction costs, it enhances transparency and trust which helps the expansion of fintech. Research on developing countries backs this claim even more. More specifically, Zhu et al. (2006) found that information technology capability is positively linked to firm performance when it suits their strategy. An international examination reveals that IT investment alone is not sufficient; moreover, performance gains only occur when technological capabilities complement organizational processes. Studies show startup firms in the area of digital entrepreneurship scale faster because they utilise innovative digital technologies. According to a study conducted by Autio, Nambisan, Thomas and Wright, digital technology makes it possible for new ventures to become scalable in a way that was not possible before.
It was found that digital technology enables platform-based models, network connectivity, and reduced marginal costs. Specifically within the financial sector, empirical studies show that fintech adoption enhances both financial inclusion and entrepreneurial financing. Gomber, Koch, and Siering (2017) examined service delivery mechanisms, operational efficiency and impact on financial interoperability in detail. In equal measure, Arner, Barberis, and Buckley (2015) claim that the effect of fintech on financial systems worldwide is to increase competition and facilitate innovation-led growth. In Africa, financial inclusion and startup growth have been closely linked to technological innovation. According to Ozili (2018), the adoption of digital finance enables greater access to financial services and costs small businesses. According to studies in eastern Africa, mobile-based payment systems and digital wallets significantly increase client acquisition, transaction volumes and scalability for fintechs.
39
Moreover, a study on the maturity of digital capability reveals that firms with strong digital strategies outperform their competitors in adaptability and market responsiveness (Westerman et al., 2014). This observation is particularly crucial to fintech startups operating in a dynamic regulatory as well as technological environment where agility is important for sustainable growth. The consolidated empirical evidence draws similar conclusions from more than ten initial studies. Here are some insights: Technological innovation allows businesses to operate more efficiently, lowers transaction cost and improves scalability, ecosystem integration, better decision-making and create more competitive advantage. Nonetheless, findings show that technology will not grow if it is not supported technically, managerially and financially. Moreover, we need an appropriate regulatory environment. As a result, the strategies of technological innovation are a direct driver of organizational growth and also serve as an enabling mechanism that enhances other post-market entry strategies. The long-term trajectory of fintech ventures in emerging economies like Nairobi is thus contingent upon their ability to maintain high innovation rates while navigating structural and institutional constraints effectively.
40
2.2.4 Managerial Capability Strategies and Organizational Growth
In technology-based high-uncertainty environments managerial capability do significantly affect organizational performance empirically the research have proven. According to studies conducted on entrepreneurship, strategic planning, and digital transformation, organizations that are led by skilled and experienced managers tend to convert resources into prolonged performance representation much easily. There is strong empirical evidence for the founder’s characteristics and firm growth relationship. According to Colombo and Grilli (2005), startups that are managed by founders who are more educated and have more industry experience have faster employment growth and innovation. The researchers Marvel and Lumpkin (2007) proved that knowledge-based managerial skills impact positively on new venture performance by initiating opportunities recognition and strategic execution. Thus, managerial human capital appears to play a key role in scalability and competitive positioning.
Stuffing on more influential people might help decision progress, but it introduces chaos in the process. According to Eisenhardt and Martin (2000), firms operating in dynamic markets achieve better outcomes when managers undertake a structured, yet flexible, process of strategic decision-making. It’s important to make timely strategic adjustments as soon as things become volatile in any environment. According to Protogerou et al (2012), in industries that experience rapid technological change, management capabilities are associated with superior performance. According to studies, growth is linked to leadership support for digital transformation. According to the findings of Westerman, Bonnet and McAfee (2014), organizations whose top management commits heavily to digital initiatives outperform competitors on profitability and revenue growth.
41
In a vast global study conducted by Kane et al. (2015), it was found that those firms with digitally savvy leadership were significantly more likely to enjoy innovations success and financial performance success. Thus, we can safely say that leadership alignment is essential to converting the investment in digital to growth. Research on organizational learning confirms the criticality of managerial capability. The research by Argote and Miron-Spektor (2011) indicated that it is possible to achieve depersonalized knowledge for systematic acquisition and application. According to Flatten et al. (2011), firms that have a stronger managerial capacity to assimilate and exploit new knowledge enjoy higher levels of innovation and higher financial performance. Managerial effectiveness in coordinating learning is beneficial for improving organizational adaptability and growth. Competence in risk management also brings about performance stabilization and growth. According to Bromiley et al. data secured risk management system when effective managerial control was in place was at an advantage in terms of financial performance and less volatile.
The governance, oversight and compliance of management assumes vital significance in fintech ecosystems plagued by cyber hacks and regulatory scrutiny for sustained growth. Empirical studies also show that executive attributes affect strategic outcomes. Executive expertise and strategic orientation significantly influence organizational performance according to Carpenter, Geletkanycz, and Sanders (2004). Companies with highly experienced management teams were more likely to implement proactive strategies and thus achieve superior growth outcomes. Likewise, Peng, Wang, and Jiang (2008) proved that in emerging markets with institutional uncertainty, managerial strategic choices have a strong relationship on firm performance. Research shows that managerial capability can enhance innovation outcome.
42
An examination by O’Reilly and Tushman (2013) of various organisations in sectors such as aerospace, high technology, consumer goods, and other industries indicates that firms, under strong leaders, capable of simultaneously balancing exploration and operational excellence achieve better innovation performance and superior long-term growth than their counterparts. According to Helfat and Martin (2015), managerial capacities affect the way firms exploit and coordinate their portfolios of resource in turbulent environments. Several studies found the same things in empirical evidence. Managerial capability enhances alignment with strategy quality of decision making organizational learning risk management and execution of innovation. Above all, evidence indicates that managerial competence allows firms to calibrate benefits from financial accessibility and technology. In sectors such as fintech, where the operating environment is characterized by rapid technology change and regulatory complexity, managerial capability determines whether the organizations will be able to translate available resources into long-run growth.
Table 2.2.4: Summary of Empirical Studies on Post-Market Entry Strategies and Organizational Growth
Author & Year
Context / Focus
Key Empirical Findings
Startup Genome (2023)
Global startup ecosystems
Nairobi is strong in formation but weak in post-entry scaling and sustainability.
Partech (2022)
Africa VC landscape
Funding concentrated in later-stage startups; lacks early-stage focus.
Beck et al. (2005)
Financial constraints
Access to finance significantly improves firm growth rates in low-income countries.
Rajan & Zingales (1998)
Financial development
Developed financial systems accelerate industry growth through external finance.
Strengthen Your Managerial ResearchEvaluating the impact of managerial capability on fintech growth requires a sophisticated understanding of human capital and strategic execution. Our experts at Essay Freelance Writers specialize in organizational behavior and strategic leadership literature for MBA candidates. Ensure your thesis stands out with a robust, peer-reviewed analysis of leadership determinants in Nairobi’s tech ecosystem.Connect with a Writing Expert
43
Author & Year
Context / Focus
Key Empirical Findings
Colombo & Grilli (2005)
Founder human capital
Education and industry experience accelerate startup employment and innovation growth.
Protogerou et al. (2012)
Managerial capability
Management capabilities are associated with superior performance in rapid-change sectors.
Westerman et al. (2014)
Digital transformation
Digitally mature firms outperform peers in profitability and innovation output.
Kou et al. (2021)
Fintech innovation
AI, blockchain, and ML enhance automation, risk assessment, and scalability.
Autio et al. (2018)
Digital entrepreneurship
Digital technologies allow platform models to scale with reduced marginal costs.
Suri & Jack (2016)
Mobile money
Financial stability from digital payments fosters small business and entrepreneurial growth.
44
2.3 Summary of Research Gaps
As per World Bank (2022), OECD (2021) and existing literature, startups are considered important tools for innovation, financial inclusion and economic transformation. Many of the empirical studies in startup growth have focused on developed economies with established financial systems stable and solid regulations, and a strong innovation ecosystem, Zoltan J. Acs and David B. Audretsch (2010) noted. Mason and Brown, 2020; Autio et al., 2018. According to Mike W. Peng et al (2008); Thorsten Beck et al (2005), these studies provide information, but are inapplicable to emerging markets due to differences in institutions, financial markets, regulation, and infrastructure of emerging and developed economies. Thus, the growth determinants observed in advanced contexts may not accurately reflect the experiences of early stage fintech start-ups operating in Nairobi County.
In Africa, fintech research has largely utilized macro- or ecosystem-level approaches. According to GSMA (2023), African Union Commission (2021), and World Bank Report (2022), Sub-Saharan Africa is undergoing rapid expansion when it comes to digital infrastructure. Further, it comprises regulatory reform and financial inclusion trends. Just like the previous one, the ecosystem benchmarking by Startup Genome(2023) ranks Nairobi as having high potential, though it has continued issues with scaling up. While these analyses reveal the various constraints imposed by the structure, they do not study how individual firms strategically respond to challenges after their entry into the market nor how these responses affect the measurable growth of the organization.
45
As a result, firm-level strategic mechanisms that link finance, compliance, innovation, and managerial capability to growth remain unexplored. Much of the existing literature uses cross-sectional design and secondary datasets sourced from industry reports or aggregated financial indicators (Partech 2022; Disrupt Africa 2022). As informative as this may be, such approaches yield limited insights into the dynamic and adaptive processes associated with post-market entry growth in fintech startups. The studies on managerial capacity usually reference performance measurement which is static in nature and does not capture the feedback loop between strategic decisions and regulatory change, capitalization change and technological disruption (Colombo & Grilli, 2005; Protogerou et al., 2012). This results in a methodological gap in understanding the interactive and evolving nature of growth strategies in the fintech ecosystem in Nairobi.
When applied to the emerging context of fintech, the concept of dominance has provided useful foundational insight but has limitations in its applicability. The Resource-Based View (Barney, 1991) emphasizes the importance of resource heterogeneity and sustainability, while Porter’s competitive positioning framework (Porter, 1980) stresses on industry structure and competitive forces. As a result, these models assume relative stability of institutions and predictable competitive dynamics. Despite their success, Fintech startups in Nairobi, Kenya, operate in an environment of evolving regulation, uncertainty of funding, fast-evolving technology, and institutional uncertainty. Scholars suggest that these contexts necessitate more adaptive and environment-sensitive explanations of performance (Peng et al., 2008; Teece, 2007).
Identify and Bridge Research GapsA strong research gap analysis is what separates a standard MBA thesis from a high-impact research project. Our team at Essay Freelance Writers excels in identifying the missing links between global fintech theories and the local realities of the “Silicon Savannah.” Secure your academic authority by ordering a meticulously synthesized summary of research gaps tailored for the Nairobi context.Order My Gap Analysis
46
Traditional models insufficiently capture the fluidity of resource access and the dependence on outside capital, not to mention the iterative nature of digital innovation in emerging markets. This study closes this theoretical gap by leveraging Pecking Order Theory (Myers & Majluf, 1984), Institutional Theory (Scott, 2008), the Technology–Organization–Environment framework (Tornatzky & Fleischer, 1990) and Dynamic Capabilities perspective (Teece, 2007) for a more context-specific post-market entry growth explanation. In a conceptual sense, previous empirical studies often consider access to finance (Beck et al., 2005; Rajan & Zingales, 1998), technological innovation (Nambisan et al., 2019; Kou et al., 2021), regulatory environment (Arner et al., 2015), and managerial capability (Westerman et al., 2014; Carpenter et al., 2004) as independent determinants of firm performance.
Although each stream of literature sheds light on an aspect, their fragmented treatment ignores the interdependence of these variables. In practice, how much capital is available affects the decision to invest in technology, how legislation is met affects the operational structure and managerial capacity affects the extent to which both financial and technology is put to use. The managerial capacity to align strategies, manage risks and execute innovation is found to be supported by empirical evidence (O’Reilly & Tushman, 2013; Protogerou et al., 2012). The roles of managerial capability in translating financial and technological strategies into sustained growth of organizations are yet to be examined in fintech in emerging economies.
47
Nairobi is a unique environment for fintech and it deserves empirical study. Nairobi – often dubbed the ‘Silicon Savannah’ boasts high mobile money penetration, a vibrant regulatory environment, and a clustered but unpredictable venture capital ecosystem. Regional analyses by Deloitte (2022) and World Bank (2022) recognize the growth of fintech in East Africa, however mostly aggregate the findings at national or global level. The differences within countries are masked through such broad aggregation, limiting a clear understanding of post-market growth in specific local contexts. Although Nairobi is a fintech hub, firm-level empirical evidence on strategic responses to financing constraints, regulatory complexity, technology adoption, and management capability in Nairobi is scarce.
In short, gaps remain in the empirical, methodological, theoretical, conceptual and contextual growth of fintech research. A number of studies have focused on ecosystems based on stable market theories. In order to fill these gaps, this study will seek to establish the extent to which access to finance, regulatory compliance, technological innovation, and managerial capability influence organizations growth of early-stage fintech startups in Nairobi County. The study will enhance understanding of the dynamics of fintech growth in emerging digital economies by adopting a firm-level, strategy-oriented and context-specific orientation, which is based on primary data.
48
CHAPTER THREE: RESEARCH DESIGN AND METHODOLOGY
3.0 Introduction
The methodology adopted for the study on post-market entry strategies and organizational growth for early Fintech startups in Nairobi County, Kenya are presented in this chapter. The chapter described research philosophy, research design, target population, sampling procedures, data collection instrument, data collection process, validity and reliability, data analysis procedure and ethical considerations that were followed during the study.
3.1 Research Philosophy
The research will employ a pragmatic research philosophy. It seeks practical solutions to real-world problems through the use of quantitative and qualitative approaches. Pragmatism is the belief that knowledge is both objective and subjective. Complexity of a multi-dimensional social-economic phenomenon often needs to be objectively measured, but at the same time may need subjective interpretation (Saunders, Lewis, & Thornhill, 2019). An appropriate research design for post-market entry growth of early stage fintech startups in Nairobi is pragmatic approach. This allows for the collection and analysis of multiple data sources to capture the nuanced realities of fintech operations. The measurable touchpoints of quantitative data, including access to finance, market adoption, technological innovation, regulation compliance, and talent availability, and qualitative data of inclusion of founder experience, business decision making, and adaptation to an emerging challenge will be studied.
49
By integrating these views, we are able to obtain an enriched understanding of the fast-evolving fintech landscape in Nairobi. It also helps in formulating practical recommendations for fintech entrepreneurs, investors and policymakers whose research output is contextually relevant and practically useful (Creswell & Plano Clark, 2018; Tashakkori & Teddlie, 2010).
3.2 Research Design
The study will adopt a descriptive and explanatory mixed-methods research design. This approach is employed to enhance analytical rigor and depth. Combining quantitative and qualitative techniques allows for complementary strengths; statistical measurement of relationships alongside contextual interpretation of strategic behavior (John W. Creswell & Vicki L. Plano Clark, 2018; Abbas Tashakkori & Charles Teddlie, 2010). The quantitative data collected by using structured survey will allow testing the hypothesis and generalizable inference with the sampled population, but the qualitative data will be collected from semi-structured interviews which will provide insight to the managers on the decision whichever was taken by them, how the regulation will be navigated, and what they done to innovate (Alan Bryman, 2016). This descriptive aspect will help to assess whether early-stage fintech startups operating in Nairobi City County have entered the market. It will also come out with what finance access, regulatory compliance, technology, and managerial skills have been developed. A descriptive design is systematic and factual representation of some phenomenon in its natural settings (Mark N. K. Saunders et al., 2019).
Strengthen Your MethodologyChoosing between pragmatism, positivism, or interpretivism can be a defining moment for your Master’s thesis. Our senior researchers at Essay Freelance Writers specialize in crafting robust mixed-methods designs that align perfectly with your research objectives. Ensure your methodology chapter stands up to the most rigorous academic scrutiny by consulting with our strategic management experts today.Refine My Methodology
50
The explanation will show the relation of any post-market entry strategy in organizational growth. Explanatory research involves analysing relationships between various factors and it can help determine the degree of impact various factors have on one another (John W. Creswell & J. David Creswell, 2018). This design supports situational assessment and causal analysis. Using both breadth and depth, the research produces results that are statistically robust and contextually grounded. This enables us to offer conclusions that may inform policy and managerial practice in Kenya’s early-stage fintech sector.
3.3 Target Population
The target population for this study comprises all active early-stage fintech startups operating in Nairobi City County. The two background mentioned early-stage fintech startups are registered, tech-driven financial service firms that have been operational for more than one year but not more than five years and pursuing growth through scaling, acquiring customers, and increasing revenue. As per findings of RegTech Africa (2023) and Kenya National Innovation Agency (2024), there are about 115 early-stage fintech startups in Nairobi, making it the leading fintech hub in Kenya. Hence, the accessible target population (N = 115) for this study comprises of 115 firms. The study undertakes a unit of analysis of fintech startup to study the effects of post-market entry strategy on organizational growth at the firm level. The unit of observation consists of founders, co-founders, and senior managers who decide strategically. They have the most information with regard to financing strategies, regulatory compliance, technological innovation, and managerial capability.
51
3.4 Sample Size and Sampling Procedure
The study will employ two complementary sampling techniques to comprehensively capture both quantitative and qualitative insights on post-market entry strategies and organizational growth of early-stage fintech startups. The target population of the study as compiled by RegTech Africa (2023) and KENIA (2024) is approximately 115 early-stage fintech startups in Nairobi City County. Calculation of sample size using Yamane (1967) formula:
The sturdy will focus exclusively on fintech startups, ensuring sectoral specificity and analytical precision, given that fintech firms operate within highly regulated and innovation-driven environments that directly shape post-entry growth dynamics. This sample of 89 startups provides a statistically significant representation of the Nairobi fintech ecosystem for the quantitative survey phase of the research.
52
Accordingly, the quantitative survey will select 89 fintech startups. After the stratification, a simple random sampling method will be used. All eligible fintech startups will have a complete list prepared assigning ID numbers through random number generator, the required sample will be selected at random from this list. One key informant responsible for strategic and operational management, which is the principal decision maker, will fill in the survey from every selected startup. It guarantees that the responses reflect the firm-level strategic practices for access to finance, regulatory compliance, technology innovation, and managerial ability. To explore the qualitative aspect, semi-structured interviews will be held to uncover in-depth strategic decision-making and growth experiences. According to Michael Quinn Patton (2015), they are suitable for use when analysing complex organisational processes, with flexibility to be able to probe emerging themes. The interviews’ participants will be chosen purposively. The participants will include founders of fintech start-ups that have scaled successfully, as well as experts from incubators, accelerators and institutions of financial innovation. Also, snowball sampling will be used to find more eligible people, particularly whether scaled startups who are not easily found via public databases. This methodology is appropriate for entrepreneurial studies whose target respondents are difficult to directly reach (John W. Creswell & Vicki L. Plano Clark, 2018).
3.5 Description of Research Instruments
The research will include various instruments suitable for the mixed-methods approach adopted for the study as per the condition for enhancing the depth and validity of the analysis (John W. Creswell & Vicki L. Plano Clark, 2018; Abbas Tashakkori & Charles Teddlie, 2010). The information obtained will be presented, analysed using descriptive statistics and methods specifically relevant to the study. Moreover, it encompass various aspects of post-market entry strategies and their implication on the growth of early-stage fintech startups in Nairobi City County. The main quantitative instrument will be structured questionnaires that will be designed to measure and collect ordinal data on our study variables which are access to finance, regulatory compliance, Technological innovations, Managerial capability and Organizational growth. The closed-ended statements will be assessed through the questionnaire with the help of five point Likert scale. The scale will range in ordinal fashion from 1 = Strongly Disagree to 5 = Strongly Agree. This scale will yield a set of standardised ordinal responses. The following sections will be created in the questionnaire:
53
Section A: This part will provide information about the firm and respondent profile which includes firm age, size, ownership pattern and duration for which he is operating. Once the database is complete, we will be able to categorize the startups and see how the characteristics of the firm influence growth dynamics. Section B: This part will assess the degree to which fintech startups access the financing. It will look at the availability of credit facilities, access to venture capital and other sources of finance, adequacy of working capital, and financial support as well. The objective is to examine how access to finance hinders the growth and sustainability of fintech startups. Section C: This section explains how startups react and cope with regulatory requirements. The study will review the compliance frameworks and licensing status, regulatory adaptability, engagement with regulators, and ability to align business model with policies. The goal here is to find how regulatory strategies affect safety and growth. Section D: This section evaluates the extent of technological capability of the startups. The focus will be on product innovation, system upgrades, digital infrastructure, automation systems, cybersecurity measures, and investment in research and development. This part of the essay seeks to explore how technological innovation contributes to competitiveness and growth of the firm. Section E: The measurement of managerial capabilities- a strategic growth driver will be done here. Factors for consideration in the analysis will include effective leadership, strategic decision making, allocation of resources, risk management and spotting market opportunities. The data collected will reveal how managerial capabilities affect the growth of the fintech startup.
54
Section F will highlight the study’s dependent variable. We will measure the growth of the organization through subjective and objective measures such as revenue growth, profitability growth, growth in customer base, and growth in market share. To protect identity and achieve comparable responses with other firms, the respondents will measure growth performance by their firm using standardized Likert scale items. To complement the survey, a qualitative component research will use semi-structured interview guides to obtain in-depth insights into how Firms adapt their strategies, manage their innovations and their growth experience. According to Michael Quinn Patton (2015), the semi-structured interview method enabled the exploration of key themes in the interview while allowing flexibility to probe into an issue that emerged during the interview that was relevant to the startup’s growth. The target is twenty founders who have scaled their fintech startups past the early-stage. Purposive sampling will be executed to select the required participants. Where necessary, snowball sampling will be applied to identify more scaled firms.
3.6 Pilot Testing
To determine whether the research instruments are clear, relevant and practical, the researcher will conduct a pilot test before the actual data collection. The pilot study aims to find out ambiguous questions, time consumed for their use and errors and mistakes in measurement to be avoided before actual use. The additional pre-testing is mainly used to ensure that the questions asked are understood by the respondents and relevant to the research objective. According to Saunders, Lewis, and Thornhill (2019), it improves the quality of the instruments. A small number of samples will be drawn from early stage fintech startups which are outside the sample and not part of the study. The wording of the questionnaire and the interview guide, the structure and flow, and the consistency including the use of similar words will be refined through the feedback received from the respondents. We will make appropriate changes to improve the accuracy as well as understanding of the respondents before the final data collection phase.
Maximize Data Reliability & ValidityDeveloping high-quality research instruments is a foundational step for any MBA candidate. At Essay Freelance Writers, we help you design robust Likert scales, structured questionnaires, and semi-structured interview guides that meet the highest academic standards. Ensure your pilot study effectively refines your research tools to guarantee significant and defensible findings in your final thesis.Order Instrument Design
55
3.7 Validity and Reliability
As stated by William M. K. Trochim (2006), the validity of the research instrument is the extent to which it measures what it is intended to measure. It is the degree to which a finding is able to accurately measure the concept or variable you want to study. The research instruments to be used for this study will be developed based on theory and empirical literature on post-market entry strategies and organizational growth. In accordance with Saunders, Lewis and Thornhill (2019), an expert review will also be carried out. It will determine whether the items are clear, relevant, and adequate. In order to find out whether the measurement items load on the right variable, the construct validity will be checked using the factor analysis test. According to Creswell and Plano Clark, 2018, factor analysis helps confirm the fit of the observed indicators to the theoretical indicators. The final analysis will include only the items with acceptable factor loading. According to Reliability, as per Cronbach (1951), it refers to the extent to which a research instrument yields the same results upon repeats under similar circumstances. To ensure internal consistency of the questionnaire, we will test Cronbach’s alpha coefficient. As Cronbach (1951) suggested, any reliability value greater than or equal to 0.70 will be acceptable. To have good internal consistency, the items measuring the same construct need to correlate adequately. To assist in achieving consistency across participants, a standardized interview guide will be used to enhance reliability for qualitative component. Audio recordings of the interviews (with consent) will also be made and transcribed verbatim to minimize interpretation errors. According to Denzin (2012), these procedures improve the dependability and credibility of qualitative findings.
56
3.8 Data Collection Procedures
To ensure the methods are rigorous and ethical, and to provide adequate coverage of the objectives, data collection will be done in a systematic manner. The researcher will get an introduction letter from the university authorizing the study and aiding access to the fintech start-ups in Nairobi City County. The certificate validates the research and facilitates collaboration among participants, according to Creswell and Creswell (2018). Various mechanisms such as emails invitations, LinkedIn, and phone calls will be used to recruit participants. In light of ethical research standards (Mugenda & Mugenda, 2019), we will inform Participants clearly about the aims of the study, the confidentiality and voluntary nature of their participation. These outreach strategies are effective for engaging busy professionals in entrepreneurial ecosystems (Saunders, Lewis, & Thornhill, 2019). As indicated by Creswell & Plano Clark (2017), the mixed-methods approach can be used for this particular study. It can enhance credibility and validity through triangulation. To obtain quantitative data, we will administer our own structured questionnaire both manually and with Google Forms. Each fintech startup will give one reply of a founder, co-founder or senior manager. The data collected would be analysed using Statistical Package for the Social Sciences (SPSS) software using descriptive and inferential statistics (regression analysis) to determine the significant impact of independent variables (access to finance, market adoption, talent and competition) on dependent variable (organizational growth). There is a connection between the data collection instrument and data analysis tool, and this connection is aligned with the quantitative research design. Reminder messages will be sent to those who have not answered the survey at set intervals to increase responses.
57
For the qualitative part, semi-structured interviews will be conducted virtually or face-to-face depending on participants availability. The interviews will feature interviews with purposefully sampled founders of profitable ventures and experts from Incubators, accelerators, and support institutions. Insights into strategic adaptation, innovation management, leadership and ecosystem dynamics can be obtained through these interviews associated with fintech. Qualitative data will be analyzed using NVivo software in line with thematical analysis to capture the main themes, patterns and relationships that arise from the narratives offered by the participants (Bryman, 2016). The researcher will work with major innovation centres and fintech-oriented institutions like iHub, Nairobi Garage, Moringa School and the Kenya National Innovation Agency (KENIA) to build access and credibility. These organizations help with the early stage of the venture and offer access and connections to verified networks of fintech founders (Ndemo & Weiss, 2017; KENIA, 2024). The researcher will collect secondary data from reliable sources. Possible sources will be government reports (like Kenya National Bureau of Statistics) and reports by the Kenya ICT Authority and databases of the fintech ecosystem (Partech Africa, StartupBlink, Disrupt Africa). Combining primary and secondary data allows triangulation, depth and contextualisation (Saunders, Lewis, and Thornhill, 2019). The use of multi-source and multi-method data collection strategies will facilitate a holistic, credible and contextually-grounded study of the post-market entry and organisational growth factors among early-stage fintech startups in Nairobi City County.
56
The researcher will work with major innovation centres and fintech-oriented institutions like iHub, Nairobi Garage, Moringa School and the Kenya National Innovation Agency (KENIA) to build access and credibility. These organizations help with the early stage of the venture and offer access and connections to verified networks of fintech founders (Ndemo & Weiss, 2017; KENIA, 2024). The researcher will also collect secondary data from reliable sources, including government reports (Kenya National Bureau of Statistics), the Kenya ICT Authority, and databases of the fintech ecosystem (Partech Africa, StartupBlink, Disrupt Africa). Combining primary and secondary data allows triangulation, depth and contextualisation (Saunders, Lewis, and Thornhill, 2019).
The use of multi-source and multi-method data collection strategies will facilitate a holistic, credible and contextually-grounded study of the post-market entry and organisational growth factors among early-stage fintech startups in Nairobi City County. This systematic approach ensures that both the statistical breadth and contextual depth are adequately captured to answer the core research questions.
58
3.8 Data Analysis Procedures
Once data collection is done, each response will be checked for completeness, coded and entered in SPSS. According to George A. Field (2018), SPSS (statistical package for social sciences) is one of the statistical software which widely uses to compute quantitative data and is appropriate for descriptive and inferential statistical procedures. To summarize the characteristics of the respondents and profiles of fintech startups; frequencies, percentages, means and standard deviations will be used. Multiple regression analysis will be used to test the research hypotheses and see how post-entry factors (access to finance, regulatory compliance, technological innovation, and managerial capability) affect organizational growth. The concept of a confounding variable and what it means to control for it is particularly important for multiple regression. As we will see later on, multiple regression is a statistical procedure that allows us to assess the relationship between a dependent variable and several independent variables. Furthermore, it also allows us to assess the strength of relationship and, crucially, whether this relationship is positive or negative (Andy Field, 2018). The regression model will be defined as follows:
Where: $Y$ = Organizational Growth; $AF$ = Access to Finance; $RC$ = Regulatory Compliance; $TI$ = Technological Innovation; $MC$ = Managerial Capability; $beta_0$ = Constant; $beta_1–beta_4$ = Coefficients; and $epsilon$ = Error term. We will be conducting hypothesis test at significance level of 0.05 ($alpha = 0.05$). It is widely used in social sciences for testing hypothesis. A 5% level of significance means there is 5% probability that a Type I error (rejecting a true null hypothesis) is made. This level is often employed in inferential statistical analysis (Ronald A. Fisher, 1925; Andy Field, 2018). Using regression coefficients and p-values we will determine the statistical significance, direction and magnitude of the effect of each independent variable on fintech growth.
59
3.9 Data Analysis
The information that will be extracted from the semi-structured interviews with the founders and experts will be analysed using thematic analysis for the qualitative data. According to Braun and Clarke (2006), thematic analysis is employed to identify, analyze and interpret patterns within qualitative data. This is effective in getting an insight into contextual experience and processes (Creswell, 2018). The interviews will be transcribed, systematically coded, and organized into emerging sections reflecting financial access, regulatory compliance, technological innovation, and managerial capabilities. Through triangulation, we will be able to achieve integration of the quantitative and qualitative findings by comparing and combining the results from different data sources or methods to improve the validity and completeness of research findings. Triangulation enables cross-verification of evidence, identification of convergence or divergence in results, and strengthens the confidence in the conclusions made in the study (Norman K. Denzin, 1978; John W. Creswell & Vicki L. Plano Clark, 2018). Combining numeric relationships with participant inputs delivers research outcomes that are more credible and interpretable than what would be possible using only one method.
3.10 Diagnostic Tests
We will carry on diagnostic tests to make sure that all the assumptions of regression are met. Shapiro-Wilk test and Q-Q plots will be used to assess normality of residuals. The presence of multicollinearity among the independent variables will be tested using the Variance Inflation Factor (VIF). A VIF value of less than 10 indicates no serious multicollinearity issue. Scatterplots would be used to assess linearity of each well in a linear model. To verify homoscedasticity (constant variance of error), residual plots and Breusch–Pagan test would be conducted. Also, the independence of errors will be checked using the Durbin-Watson statistic with acceptable values being close to 2. These tests will enhance the validity and reliability of the regression results.
Reliable Data Analysis for MBA SuccessInterpreting multiple regression models and thematic patterns requires advanced analytical skills. Our team at Essay Freelance Writers provides comprehensive SPSS and NVivo support to help you transform raw data into a compelling research story. Ensure your Chapter Four and Chapter Five meet the highest academic standards by partnering with our senior statistical analysts today.Order My Data Analysis
60
3.11 Ethical Considerations
The research will strictly observe ethical principles as laid down in research ethics standards (National Commission for Science, Technology and Innovation n.d.; Catholic University of Eastern Africa n.d.). As participation in this study will be purely on voluntary basis, written informed consent will be taken from respondents before data collection. The researcher will inform the study participants the purpose of the study, their right to withdraw any time, and the confidentiality measures that are taken. The confidentiality and anonymity of the participants will be ensured and no personal or proprietary information will be revealed. The data collected will only be utilized for scholarly purposes and kept in a safe place to prevent mishandling. Mixed research tools will be utilized for data collection on post-market entry strategies and overall influence on the growth early-stage fintech startups in Nairobi City County. The instruments will only be used after informed consent by the participants. The interviews will be recorded with permission. By ensuring that the study has a mixed-methods design and ethical research standards the research will collect depth and breadth of the data. Adhering to these ethical guidelines ensures the integrity of the research process and protects the rights and well-being of all participants involved in the study of Nairobi’s fintech ecosystem.
61
REFERENCES
African Union Commission (AUC). (2021). Innovation and entrepreneurship in Africa: Policy report. African Union.
Ashiru, G. (2025). Startup graveyard report: Governance gaps contribute to high failure rates in Africa’s startups. Tech in Africa. https://www.techinafrica.com/2024-startup-graveyard-report-governance-gaps-contribute-to-high-failure-rates-in-africas-startups/
Autio, E., Nambisan, S., Thomas, L. D. W., & Wright, M. (2018). Digital affordances, spatial affordances, and the genesis of entrepreneurial ecosystems. Strategic Entrepreneurship Journal, 12(1), 72–95.
Barney, J. (1991). Firm resources and sustained competitive advantage. Journal of Management, 17(1), 99–120. https://doi.org/10.1177/014920639101700108
Beck, T., & Demirgüç-Kunt, A. (2006). Small and medium-size enterprises: Access to finance as a growth constraint. Journal of Banking & Finance, 30(11), 2931–2943. https://doi.org/10.1016/j.jbankfin.2006.05.009
CB Insights. (2023). The top 20 reasons startups fail. CB Insights Research.
Collis, D. J., & Montgomery, C. A. (1995). Competing on resources: Strategy in the 1990s. Harvard Business Review, 73(4), 118–128.
Cooper, D. R., & Schindler, P. S. (2014). Business Research Methods (12th ed.). New York: McGraw-Hill Education.
Creswell, J. W., & Creswell, J. D. (2018). Research Design: Qualitative, Quantitative, and Mixed Methods Approaches (5th ed.). Thousand Oaks, CA: Sage Publications.
Deloitte. (2022). The future of work in Africa: Building tech talent for the digital economy. Deloitte Insights.
Extensia. (2024). Early-stage fintech funding trends in Africa. https://extensia.tech/early-stage-fintech-funding-trends-in-africa/
62
Feldman, M., Siegel, D. S., & Wright, M. (2019). New developments in innovation and entrepreneurial ecosystems. Industrial and Corporate Change, 28(4), 817–826.
Finnovating for Africa. (2023). Reimagining the African financial services landscape. https://www.scribd.com/document/666451482/Finnovating-for-Africa-2023-Reimagining-the-African-financial-services-landscape
Government of Kenya. (2021). Kenya Vision 2030 progress report. Ministry of Planning and National Development.
GSMA. (2022). The mobile economy: Sub-Saharan Africa 2022. GSMA Association.
Hall, R. (1992). The strategic analysis of intangible resources. Strategic Management Journal, 13(2), 135–144. https://doi.org/10.1002/smj.4250130205
Kenya National Innovation Agency (KENIA). (2024). National Innovation Ecosystem Report. Nairobi: KENIA.
Kothari, C. R. (2014). Research Methodology: Methods and Techniques (2nd ed.). New Delhi: New Age International Publishers.
Kraaijenbrink, J., Spender, J. C., & Groen, A. J. (2010). The resource-based view: A review and assessment of its critiques. Journal of Management, 36(1), 349–372. https://doi.org/10.1177/0149206309350775
Mason, C., & Brown, R. (2020). Creating good public policy to support high-growth firms. Small Business Economics, 54(2), 421–436.
63
Mugenda, O. M., & Mugenda, A. G. (2019). Research Methods: Quantitative and Qualitative Approaches. Nairobi: Acts Press.
Newbert, S. L. (2007). Empirical research on the resource‐based view of the firm: An assessment and suggestions for future research. Strategic Management Journal, 28(2), 121–146. https://doi.org/10.1002/smj.573
Osifeso, D. (2026). Fintech funding in Africa: New trends in 2026. Africa Tech Business. https://www.africatechbusiness.com/posts/fintech-funding-in-africa-new-trends-in-2026
Partech. (2023). 2022 Africa tech venture capital report. Partech Partners.
Patel, P. (2021). Founder burnout: Causes, consequences, and coping strategies in startups. Entrepreneurship Theory and Practice, 45(6), 1458–1479.
Penrose, E. T. (1959). The theory of the growth of the firm. Oxford University Press.
Peteraf, M. A. (1993). The cornerstones of competitive advantage: A resource‐based view. Strategic Management Journal, 14(3), 179–191. https://doi.org/10.1002/smj.4250140303
Porter, M. E. (1980). Competitive Strategy: Techniques for Analyzing Industries and Competitors. Free Press.
Priem, R. L., & Butler, J. E. (2001). Is the resource‐based “view” a useful perspective for strategic management research? Academy of Management Review, 26(1), 22–40. https://doi.org/10.5465/amr.2001.4011928
Saunders, M., Lewis, P., & Thornhill, A. (2019). Research Methods for Business Students (8th ed.). Harlow: Pearson Education Limited.
Teece, D. J., Pisano, G., & Shuen, A. (1997). Dynamic capabilities and strategic management. Strategic Management Journal, 18(7), 509–533.
World Bank. (2022). Africa’s digital transformation: Leveraging innovation for inclusive growth. World Bank Publications.
Finalize Your Research with ExcellenceYou have successfully compiled your research proposal. For the next phase of your academic journey—data analysis, results discussion, and final defense preparation—Essay Freelance Writers is here to support you. Let our senior consultants help you transform this proposal into a groundbreaking MBA thesis.Start My Dissertation Phase
64
APPENDICES
Appendix 1: Study Schedule
The study will run from October 2025 to May 2026, progressing through key stages as outlined in the table below. These include proposal development and approval, obtaining research authorization, data collection, analysis, report writing, and final submission. This schedule ensures the timely and systematic completion of the research activities.
Activity
Oct-25
Nov-25
Dec-25
Jan-26
Feb-26
Mar-26
Apr-26
May-26
Proposal development & submission
XXXX
University & NACOSTI approval
XXXX
Data collection
XXXX
XXXX
XXXX
Data analysis & interpretation
XXXX
Report writing
XXXX
XXXX
Final editing & submission
XXXX
65
Appendix 2: LIST OF EARLY-STAGE FINTECH IN NAIROBI
The following table provides a comprehensive list of 115 early-stage fintech startups currently operating within Nairobi City County. These firms represent various sub-sectors including Payments, Credit, Insurtech, Wealth Management, and Crypto infrastructure.
No
Company
Category
Description
Notes
1
ImaliPay
Payments
Earned wage access for gig workers
Nairobi-based
2
Wapi Pay
Payments
Cross-border B2B payments
Nairobi-based
3
Peach Payments
Payments
Online payment processing for SMEs
Nairobi-based
4
Payd
Payments
Digital payments and collections
Early-stage
5
Paylink
Payments
Payment links for merchants
Early-stage
6
Chumz Pay
Payments
Social savings and payments
Early-stage
7
Lipa World
Payments
International remittances
Early-stage
8
Koa Pay
Payments
Mobile-based payment solutions
Early-stage
9
PesaKit
Payments
Digital wallet and payments
Early-stage
10
Paylend
Payments
Payments with short-term credit
Early-stage
11
Zazu Africa
Payments
Neobank services
Early-stage
12
PayDay Africa
Payments
Salary-linked advances
Early-stage
13
PaySoko
Payments
SME checkout solutions
Early-stage
14
PayFlow Africa
Payments
Business payment automation
Early-stage
15
Tuma App
Payments
Mobile money transfers
Early-stage
16
Umba
Credit
Digital bank offering loans
Nairobi-based
17
Pezesha
Credit
SME lending infrastructure
Nairobi-based
18
Imarika
Credit
SME working capital loans
Early-stage
66
19
SalaryPay
Credit
Salary-backed employee credit
Early-stage
20
Fundi Africa
Credit
Education and SME financing
Early-stage
21
Jijenge Credit
Credit
Micro and SME lending
Early-stage
22
Boost Credit
Credit
Short-term digital credit
Early-stage
23
LendXS
Credit
Alternative lending platform
Early-stage
24
QuickCash Africa
Credit
Instant mobile loans
Early-stage
25
PesaAdvance
Credit
Short-term digital credit
Early-stage
26
Lami
Insurtech
Digital insurance infrastructure
Nairobi-based
27
Turaco
Insurtech
Embedded micro-insurance
Nairobi-based
28
Pula Advisors
Insurtech
Agricultural insurance analytics
Nairobi-based
29
BimaNow
Insurtech
Digital insurance distribution
Early-stage
30
DigiCover Africa
Insurtech
Online insurance products
Early-stage
31
Hisa
Wealth
Retail investment platform
Nairobi-based
32
Kwara
Wealth
Digital SACCO management
Nairobi-based
33
Chumz
Wealth
Goal-based savings
Early-stage
34
MaliPlus
Wealth
Personal finance/investments
Early-stage
35
DigiSacco
Wealth
SACCO digitization
Early-stage
36
Kotani Pay
Crypto
Crypto to mobile money rails
Nairobi-based
37
ChainAfrica
Crypto
Blockchain infrastructure
Early-stage
38
BitSoko
Crypto
Bitcoin-based payments
Early-stage
67
Note: Companies listed from index 41 onwards represent subsequent evaluation batches within the target population.
39
StablePay Africa
Crypto
Stablecoin payment solutions
Early-stage
40
Web3Pay KE
Crypto
Web3 blockchain payments
Early-stage
41
ImaliPay
Payments
Earned wage access
Nairobi-based
42
Wapi Pay
Payments
Cross-border B2B payments
Nairobi-based
43
Peach Payments
Payments
SME payment processing
Nairobi-based
44
Payd
Payments
Digital collections platform
Early-stage
45
Paylink
Payments
Merchant payment links
Early-stage
46
Chumz Pay
Payments
Social savings platform
Early-stage
47
Lipa World
Payments
International payments
Early-stage
48
Koa Pay
Payments
Mobile payment solutions
Early-stage
49
PesaKit
Payments
Digital wallet
Early-stage
50
Paylend
Payments
Short-term credit/payments
Early-stage
51
Zazu Africa
Payments
Neobank services
Early-stage
52
PayDay Africa
Payments
Salary-linked advances
Early-stage
53
PaySoko
Payments
SME checkout solutions
Early-stage
54
PayFlow Africa
Payments
Payment automation
Early-stage
55
Tuma App
Payments
Money transfers
Early-stage
56
Umba
Credit
Digital bank loans
Nairobi-based
57
Pezesha
Credit
SME lending platform
Nairobi-based
58
Imarika
Credit
SME working capital
Early-stage
68
59
SalaryPay
Credit
Salary-backed credit
Early-stage
60
Fundi Africa
Credit
Education financing
Early-stage
61
Jijenge Credit
Credit
Micro/SME lending
Early-stage
62
Boost Credit
Credit
Short-term digital credit
Early-stage
63
LendXS
Credit
Alternative lending
Early-stage
64
QuickCash Africa
Credit
Instant mobile loans
Early-stage
65
PesaAdvance
Credit
Short-term credit
Early-stage
66
Lami
Insurtech
Insurance API infrastructure
Nairobi-based
67
Turaco
Insurtech
Embedded micro-insurance
Nairobi-based
68
Pula Advisors
Insurtech
Agri-insurance analytics
Nairobi-based
69
BimaNow
Insurtech
Insurance distribution
Early-stage
70
DigiCover Africa
Insurtech
Online insurance
Early-stage
71
Hisa
Wealth
Retail investment platform
Nairobi-based
72
Kwara
Wealth
Digital SACCO management
Nairobi-based
73
Chumz
Wealth
Goal-based savings
Early-stage
74
MaliPlus
Wealth
Personal finance tools
Early-stage
75
DigiSacco
Wealth
SACCO digitization
Early-stage
76
Kotani Pay
Crypto
Crypto-fiat payment rails
Nairobi-based
77
ChainAfrica
Crypto
Blockchain payments
Early-stage
78
BitSoko
Crypto
Bitcoin payments
Early-stage
69
79
StablePay Africa
Crypto
Stablecoin solutions
Early-stage
80
Web3Pay KE
Crypto
Web3 payments
Early-stage
81
ImaliPay
Payments
Gig economy payments
Nairobi-based
82
Wapi Pay
Payments
Cross-border B2B
Nairobi-based
83
Peach Payments
Payments
SME payments
Nairobi-based
84
Payd
Payments
Digital payments platform
Early-stage
85
Paylink
Payments
Merchant links
Early-stage
86
Chumz Pay
Payments
Social payments
Early-stage
87
Lipa World
Payments
Remittance platform
Early-stage
88
Koa Pay
Payments
Mobile payments
Early-stage
89
PesaKit
Payments
Digital payment wallet
Early-stage
90
Paylend
Payments
SME credit/payments
Early-stage
91
Zazu Africa
Payments
Neobank platform
Early-stage
92
PayDay Africa
Payments
Salary-linked advances
Early-stage
93
PaySoko
Payments
Merchant checkout
Early-stage
94
PayFlow Africa
Payments
Payment automation
Early-stage
95
Tuma App
Payments
Money transfers
Early-stage
96
Umba
Credit
Digital bank loans
Nairobi-based
97
Pezesha
Credit
Lending infrastructure
Nairobi-based
98
Imarika
Credit
Working capital loans
Early-stage
70
99
SalaryPay
Credit
Salary-backed credit
Early-stage
100
Fundi Africa
Credit
SME and Education financing
Early-stage
101
Jijenge Credit
Credit
Micro/SME lending
Early-stage
102
Boost Credit
Credit
Short-term digital credit
Early-stage
103
LendXS
Credit
Alternative lending
Early-stage
104
QuickCash Africa
Credit
Mobile loans
Early-stage
105
PesaAdvance
Credit
Digital short-term credit
Early-stage
106
Lami
Insurtech
Insurtech infrastructure
Nairobi-based
107
Turaco
Insurtech
Micro-insurance for workers
Nairobi-based
108
Pula Advisors
Insurtech
Agricultural insurance
Nairobi-based
109
BimaNow
Insurtech
Digital distribution
Early-stage
110
DigiCover Africa
Insurtech
Insurance online
Early-stage
111
Hisa
Wealth
Trading and investment
Nairobi-based
112
Kwara
Wealth
SACCO digitisation
Nairobi-based
113
Chumz
Wealth
Goal-based savings
Early-stage
114
MaliPlus
Wealth
Personal investment platform
Early-stage
115
DigiSacco
Wealth
SACCO platform
Early-stage
71
Appendix 3: RESEARCH QUESTIONNAIRE, CONSENT FORM, AND INTERVIEW GUIDEInformed Consent Form
You are invited to participate in a study examining post-market entry strategies and organizational growth of early-stage fintech startups in Nairobi City County. Participation is voluntary, and you may withdraw at any time without penalty. All information provided will be treated with strict confidentiality and used solely for academic purposes.
☐ I consent to participate in this study
☐ I consent to audio recording (interview participants only)
Please read each statement carefully and tick (✔) the option that best represents your opinion based on a 5-point Likert scale: 1 = Strongly Disagree, 2 = Disagree, 3 = Neutral, 4 = Agree, 5 = Strongly Agree.
Section A: Firm and Respondent Profile
A1. Name of Firm (Optional): ________________________________
A2. Position of Respondent: ________________________________
A3. Age of the Firm: ☐ Less than 1 year | ☐ 1–3 years | ☐ 4–6 years | ☐ Above 6 years
A4. Size of the Firm (Employees): ☐ 1–10 | ☐ 11–30 | ☐ 31–50 | ☐ Above 50
With a passion for helping students navigate their educational journey, I strive to create informative and relatable blog content. Whether it’s tackling exam stress, offering career guidance, or sharing effective study techniques
Length: Short, usually around 100 to 140 pages depending on the edition
If you have heard people describe this book as “a story about animals” and nothing else, yeah. That is technically true. But much like how the vibrant surface of Breakfast at Tiffany’s hides deeper melancholic themes, it is also the kind of book that makes you pause mid page and go, wait. I know exactly who this is about.
It is fast to read, simple on the surface, and then it keeps unfolding in your head for days.
Struggling to decode the complex political allegories in your literature assignment? Our academic experts provide deep-dive analysis that guarantees top marks for your next paper. Let us handle the heavy lifting while you focus on what matters most.
Animal Farm is about a group of farm animals who overthrow their human owner and try to build a new society where everyone is equal and work is shared fairly. At first it feels hopeful and almost wholesome. Then power starts to concentrate, rules begin to shift, and the dream of equality gets rewritten in real time.
It is basically a cautionary tale about revolutions and what can happen after the cheering stops.
Plot Summary
The animals on Manor Farm are tired of being exploited by Mr. Jones, a drunk and negligent farmer. Inspired by the dream of an old pig named Old Major, they imagine a future where animals run the farm for themselves.
After Old Major dies, two pigs, Snowball and Napoleon, step up as leaders. The animals successfully rebel, chase Mr. Jones away, and rename the place Animal Farm. They create a set of principles called Animalism, meant to protect equality and fairness.
For a while, things improve. The animals work hard. Food is shared more fairly. There is pride in ownership. But the pigs begin taking privileges. A power struggle grows between Snowball, who is idealistic and organized, and Napoleon, who is quiet, strategic, and increasingly ruthless.
Eventually Napoleon removes Snowball by force and takes control. Over time, Napoleon and the pigs change the rules, rewrite history, punish dissent, and convince the other animals that sacrifices are necessary. The farm becomes what it was supposed to replace, except now the animals are being controlled by animals.
And the ending. It lands like a door closing.
Main Characters
Napoleon: A Berkshire boar who becomes the farm’s dictator.
Snowball: A pig and revolutionary leader, later exiled.
Old Major: The pig whose vision inspires the rebellion.
Boxer: A strong, loyal workhorse who believes in the cause.
Clover: A kind mare, more perceptive than she thinks she is.
Squealer: A pig who spreads propaganda and manipulates language.
Benjamin: A cynical donkey who sees what is happening but rarely acts.
Mollie: A vain mare who misses human comforts.
Mr. Jones: The original farmer, overthrown early in the story.
The dogs: Raised by Napoleon as enforcers.
The sheep: The crowd, easily led through slogans.
Analyzing characters like Napoleon and Snowball requires a professional touch to truly impress your professors. Get custom-written essays on Animal Farm character arcs from our dedicated team of literary critics today. Your perfect grade is just a few clicks away from becoming reality.
Napoleon is not charismatic in the way Snowball is. He does not have to be. His power is built through control of force, information, and fear. He plays the long game. He turns politics into survival. And he understands that if you can control the story people tell themselves, you can control almost everything.
Snowball
Snowball is clever, energetic, genuinely committed to the idea of a better future. But he underestimates how quickly ideals can be crushed by raw power. He is the kind of leader who believes persuasion will win. Orwell makes him impressive. Then makes him vulnerable.
Boxer
Boxer breaks your heart, honestly. He is pure labor and pure loyalty. His two mottos, basically work harder and trust the leader, are what authoritarian systems feed on. Boxer is what happens when goodness is exploited.
Squealer
Squealer is the most “real” character in a way, because you can recognize him immediately. He is not just lying. He is manufacturing reality. He turns contradictions into explanations, and explanations into slogans. He is the voice of propaganda.
Benjamin
Benjamin sees the truth early. He understands the pattern. But he is detached, fatalistic, tired. Orwell uses him to show how awareness without action can still end in tragedy.
Themes
Power corrupts: The pigs start as comrades and end up as rulers. The transition is gradual, which is the point. Orwell is not saying corruption arrives like a thunderstorm. It arrives like small exceptions that become permanent.
The betrayal of ideals: The revolution is supposed to create equality. Instead, the ideals are used as cover for a new hierarchy. This is one of the book’s sharpest warnings. People can be made to suffer in the name of a “future” that never arrives.
Propaganda and control of language: Squealer does not just persuade. He rewires how the animals think. Words become tools. Definitions shift. Memory gets edited.
Class and exploitation: Even without humans, exploitation continues, because the structure stays. Some plan, some command, some work until they drop. Orwell is blunt about who pays the cost.
Ignorance and manipulation: The animals who cannot read well, or cannot remember clearly, are easier to control. The book keeps returning to this. If you cannot verify, you can be convinced.
Themes of corruption and propaganda are more relevant today than ever before in modern literature studies. Secure an expertly crafted essay that bridges the gap between George Orwell and current political climates. Join our platform now to connect with a subject matter specialist instantly.
The Seven Commandments: The laws of Animalism are supposed to protect equality. As they get changed, they become a symbol of how rulers rewrite principles to justify themselves.
The windmill: The windmill is sold as progress and a better life. It becomes a tool for control, endless labor, and distraction. A promise that keeps the animals working.
Milk and apples: Early privilege. Small, almost laughable at first. Then you realize it is the beginning of a ruling class.
The dogs: They are the secret police. Fear made literal.
“Beasts of England”: A revolutionary anthem. When it gets replaced, you feel the revolution narrowing, becoming managed and sanitized.
Setting and Context
The story takes place on an English farm, but it is not really about England. It is an allegory of the Russian Revolution and the rise of the Soviet Union, especially under Stalin.
Old Major echoes Marx and Lenin type revolutionary thinkers.
Snowball is often linked to Trotsky.
Napoleon is linked to Stalin.
The purges, confessions, propaganda, show trials. They are all here, simplified into a farmyard story that somehow makes it even more chilling.
Orwell wrote it during World War II, when criticizing the Soviet Union was unpopular in some circles, especially because the USSR was an ally against Nazi Germany. That context matters. He was pushing against a tide.
Writing Style and Language
Orwell’s style is plain on purpose. Short sentences. Clear descriptions. Almost like a children’s story at first. That simplicity is part of the trap.
Because the events are brutal, but the language is calm. The calmness makes it feel normal. And that is exactly how authoritarianism tries to feel. Normal.
Literary Devices
Allegory: The whole novella functions as political allegory.
Satire: Orwell mocks hypocrisy, slogans, bureaucracy, and political doublespeak.
Irony: The farm’s “equality” becomes inequality. The “rules” are rewritten. The pigs become what they hated.
Foreshadowing: Early moments like the milk, the puppies, and the special treatment hint at what is coming.
Personification: Animals behave like humans to make political structures easier to see and criticize.
Repetition: Slogans like “Four legs good, two legs bad” show how thought can be simplified into obedience.
Need a literary devices breakdown that goes beyond the basic summaries available online for free? Our writers specialize in identifying nuanced motifs and foreshadowing techniques that earn those high-tier academic grades. Sign up today and get professional support for your literature project.
Orwell’s chapters are short and move quickly. Here is the clean version.
Chapter 1
Old Major gathers the animals and describes his dream of a rebellion. He teaches them “Beasts of England.” The idea of Animalism is born.
Chapter 2
Old Major dies. Snowball and Napoleon lead the movement. The animals rebel sooner than expected when Jones neglects them. They rename the farm and create the Seven Commandments.
Chapter 3
The animals work hard and the harvest is successful. The pigs do not do manual labor. Milk disappears. Boxer becomes the model worker.
Chapter 4
News of the rebellion spreads. Jones and men attack, but the animals win the Battle of the Cowshed. Snowball is celebrated.
Chapter 5
Mollie leaves. Snowball and Napoleon argue over the windmill. Napoleon unleashes dogs and drives Snowball away. Napoleon takes control.
Chapter 6
The windmill project begins, even though Napoleon opposed it. The pigs move into the farmhouse. Trade with humans starts. The commandments begin quietly shifting.
Chapter 7
Winter is harsh. Food is scarce. Napoleon uses fear to maintain control. The hens rebel and are punished. There are forced confessions and executions. “Beasts of England” is banned.
Chapter 8
The pigs intensify propaganda. Napoleon is treated like a hero figure. The animals discover another commandment has been altered. The farm is cheated in a deal with humans. The windmill is destroyed again.
Chapter 9
Boxer is injured. The pigs promise to help him, then sell him to the knacker. The animals are devastated but are talked out of their anger. The pigs celebrate.
Chapter 10
Years pass. The pigs become more like humans. The commandments are reduced to one final rule. The animals look from pig to man and cannot tell the difference.
Key Quotes
“All animals are equal, but some animals are more equal than others.”
“Four legs good, two legs bad.”
FAQs (Frequently Asked Questions)
What is the central theme of George Orwell’s Animal Farm?
The central theme of Animal Farm is how power corrupts and the betrayal of revolutionary ideals. The story illustrates how a quest for equality can be undermined by those who seize control, leading to new forms of oppression and exploitation.
Who are the main characters in Animal Farm and what roles do they play?
Key characters include Napoleon, a pig who becomes the dictator; Snowball, an idealistic revolutionary leader; Old Major, whose vision inspires the rebellion; Boxer, a loyal workhorse exploited for labor; Squealer, the propaganda-spreading pig; Benjamin, a cynical donkey aware of the truth; and Mr. Jones, the original human owner overthrown by the animals.
How does Animal Farm use allegory to convey its message?
Animal Farm uses farm animals and their rebellion as an allegory for political revolutions and totalitarian regimes. The story mirrors real-world events where initial hopes for equality are subverted by power struggles, propaganda, and manipulation, reflecting on historical revolutions such as the Russian Revolution.
What role does propaganda play in Animal Farm?
Propaganda is central to controlling the animals on the farm. The character Squealer manipulates language and rewrites history to justify the pigs’ privileges and suppress dissent. This demonstrates how controlling information can maintain authoritarian power.
What do symbols like The Seven Commandments and The Windmill represent in Animal Farm?
The Seven Commandments symbolize the original principles of equality that are gradually altered to serve those in power. The Windmill represents progress promised to improve life but ultimately becomes a tool for exploitation and distraction, highlighting broken promises under oppressive rule.
Why is Boxer considered a tragic character in Animal Farm?
Boxer embodies hardworking loyalty with mottos like ‘work harder’ and ‘trust the leader.’ His unwavering dedication is exploited by those in power, making him a tragic figure who suffers under authoritarianism despite his goodness and faith in the cause.
With a passion for helping students navigate their educational journey, I strive to create informative and relatable blog content. Whether it’s tackling exam stress, offering career guidance, or sharing effective study techniques
Recognizing the "AI smell" of overly balanced, sterile, and predictable paragraphs is the first step toward writing an opinion essay that feels like it was written by a person who actually has a mind.
You must pick a specific and arguable position that might feel a little uncomfortable or clear enough to disagree with instead of choosing a safe, socially acceptable stance that reads like a generic brochure.
The writing process involves starting with a human entry point like a personal moment or blunt statement, developing an uneven structure that reflects real thinking, and using at least one example that could only come from your own life or specific observations.
To sound human, you should compress your prose to say the sharp thing without padding, include a fair counterargument that specifically shows where the opposing view fails, and vary your sentence length and cadence to avoid a repetitive, robotic rhythm.
The final stages of the process require adding signature lines that are emotionally honest, editing specifically for your unique voice by reading the draft out loud, and ensuring that every single paragraph contains a clear judgment or claim.
How to Write an Opinion Essay That Doesn’t Look AI Generated
People are getting weirdly good at spotting AI writing now. Not because they’re all expert editors. Mostly because they’ve read the same kind of smooth, overly balanced, perfectly structured paragraphs a hundred times this month.
You know the ones. The essay starts with a polite hook, then it says “In today’s society”, then it gives three points with matching transitions, then it wraps up with a clean little bow. It’s not that this is “bad” writing, exactly. It’s just… sterile. And predictable. And it doesn’t feel like a person who actually cares about the topic wrote it.
So if you’re writing an opinion essay and you don’t want it to look AI generated, the goal isn’t to “trick detectors”, The goal is simpler and harder: write like you actually have a mind. A perspective. A few contradictions. A lived experience. And maybe a mild obsession with the point you’re making. Here’s how to do it. to achieve this, consider how to avoid getting caught using ai for school by ensuring that your writing reflects your unique voice and insights. Dig deep into your thoughts and express them authentically, as this will make your work more compelling and engaging. Embrace your individuality, and let it shine through every word you write.
First, understand what gives AI writing away
Before we fix it, you need to recognize it. AI flavored opinion essays tend to share the same tells. They often:
sound confident but say nothing specific
over explain obvious points
use generic examples instead of real ones
avoid taking a real risk or making a sharp claim
feel evenly paced, like every paragraph got the exact same amount of “importance”
stack transitions like “Furthermore” and “Moreover” and “in conclusion” like it’s a checklist
repeat the prompt back to the reader in different words
Also, the vibe is usually “neutral student essay” even when the topic is emotional or controversial. The writing tries to be fair to everyone, which sounds nice, but it also makes it feel like nobody is talking. Opinion writing is supposed to feel like someone is in the room. Understanding the different types of essays can help you see why the opinion piece requires a much higher level of personality than a standard report.
Generic AI-sounding essays are a fast track to mediocre grades and unimpressed readers. Our professional writers bring genuine human perspective and academic depth to every opinion piece we craft. Order your custom essay now to ensure your voice sounds authentic, persuasive, and entirely original.
Pick a position you can actually defend, not one that sounds safe
This is probably the biggest issue. People choose a topic and then pick the most socially acceptable stance, the one that won’t upset anyone, the one that sounds like a TED Talk summary. But a safe opinion essay reads like a brochure. AI loves brochure writing. Instead, pick a stance that is:
specific
arguable
a little uncomfortable
clear enough to disagree with
Not edgy for the sake of it. Just real. Example:
Bad, safe, AI shaped: Social media has both positive and negative effects on teenagers. Okay, sure. And water is wet.
Better: Social media isn’t “hurting teens” in general. It’s training them to perform their personality for an algorithm, and that’s the part we are ignoring.
Now we have a spine. We also have a claim that forces you to explain what you mean. If you’re stuck, write your thesis like you’re texting a friend, not writing for a rubric. “What I actually think is…”, “The thing nobody says out loud is…”, “I’m tired of pretending that…” That’s usually where the real opinion is hiding. To balance your strong stance with facts, you might explore how to write an informative essay to see how to weave data into your argument.
Struggling to find an arguable stance that doesn’t sound like a generic template? Our academic consultants specialize in brainstorming and developing high-stakes thesis statements that professors love to read. Let us help you find your unique angle and provide the structural support your big ideas deserve today.
“In today’s modern world, many people have different opinions about…”
No. Please. Stop. A human entry can be messy. It can be small. It can be a moment. Try one of these openings instead:
A tiny personal moment: Something that happened, even if it’s minor. “I realized I was addicted to my phone when I opened Instagram without thinking while I was literally brushing my teeth.” That’s not “evidence”. But it’s a human doorway.
A blunt statement: Just say the opinion. “Most people don’t hate remote work. They hate the way their company does remote work.”
A specific observation: Not a stat. Not a quote. Something you noticed. “Whenever a new AI tool drops, you can tell who actually writes for a living because they don’t celebrate. They get quiet.”
Notice what these do. They create texture. AI can imitate texture, sure, but most AI generated essays don’t include it because the writer didn’t supply it. Your job is to be oddly specific early. It signals a real person is driving. This strategy is similar to how to write a narrative essay, where the power lies in the specific, lived details of the story.
Let your essay have a shape that isn’t too perfect
AI writing loves symmetry. Three points. Even paragraphs. Balanced phrasing. Everything tidy. But real opinion writing often does this instead: makes a claim, explains it, goes on a mini rant, backs up and clarifies, admits a wrinkle, then lands the point harder. That uneven pacing is a feature. So yes, you can still structure your essay. You should. But don’t make it look like a template. A simple structure that feels human:
1. Here’s what I think
2. Here’s why I think it (with specifics)
3. Here’s what people get wrong about it
4. Here’s the best counterargument, and why I’m not fully convinced
5. Here’s what I’d do instead, or what I want people to notice
Perfect symmetry is a dead giveaway that your essay was generated by a machine rather than a human mind. Our professional writers understand the value of “human pacing” and create essays with natural flow and compelling emphasis. Partner with our team today to receive a custom-written paper that sounds like your most articulate self.
This gives you room to sound like you’re thinking, not reciting. You might start by developing a loose essay outline to ensure you cover all your bases before you let your voice take over.
Write in a voice that has preferences
AI tends to write in a voice that has no taste. No quirks. No mild annoyance. No humor. No rhythm. Add preferences. Real ones. Say things like: “I hate when people pretend…”, “This sounds dramatic, but…”, “To be honest, I didn’t believe this at first”, or “Maybe this is just me, but I swear…” This is how people actually argue. They don’t sound like a Wikipedia entry with feelings. Also, you don’t have to sound “academic” unless your teacher or publication demands it. Even then, you can keep the sentences alive. Academic doesn’t have to mean dead.
Use at least one example that could only come from you
This is the easiest way to make the essay not look AI generated. Add one example that is from your life, your school, your job, your community, a specific conversation, or a specific thing you saw online (and describe it like a person would).
Not: For example, a student may feel stressed.
But: Last semester, I watched a friend rewrite a scholarship essay five times, not because it wasn’t good, but because she was trying to guess what kind of “person” the committee wanted. By the end it didn’t even sound like her. That’s real. It has a scene. It has stakes. It also supports the argument without sounding like you pulled it from a generic list of examples.
Authentic examples are the “fingerprints” of a great essay that no AI can mimic successfully. Our writers can help you weave your personal experiences and observations into a sophisticated academic argument. Invest in an essay that truly represents your unique journey and perspective by contacting our writing team right now.
If you don’t want to use personal stuff, fine. Use a very specific public example. Not “research shows”. Use an actual thing. A specific policy at your school. A rule at your workplace. A particular ad campaign. A specific trend. A direct quote from a real person you know (with permission). Something grounded. For example, if you are working on a broader project, understanding how to write a thematic essay can help you connect these small examples to a larger central theme.
Stop padding. Say the sharp thing.
AI writing inflates. It uses a lot of words to avoid committing. Opinion essays that sound human usually do the opposite. They compress. Instead of: “There are many reasons why this issue is important and should be considered carefully by society.” Say: “We keep calling it ‘an issue’ so we don’t have to change anything.” Instead of: “This topic has generated much debate among individuals from various backgrounds.” Say: “People argue about this because admitting the truth would be inconvenient.” You’re not being dramatic. You’re being clear. A trick: after you write a paragraph, ask yourself, “What am I actually trying to say?” Then write that as one sentence. You might find the real paragraph hiding inside it.
This clarity is essential when you are learning how to write a great college essay, where word counts are tight and impact is everything. You need to get to the point before the admissions officer moves to the next file.
Include a counterargument, but don’t do the fake “both sides” thing
A lot of essays do this: “Some people think X. Others think Y. Both sides have valid points.” That’s the AI special. It sounds reasonable, but it’s empty. A better approach:
1. present the best counterargument
2. admit what’s compelling about it
3. show where it fails, specifically
4. adjust your stance if needed
This is what real thinkers do. They don’t pretend the other side is stupid. They also don’t pretend every side is equally correct. This balanced but firm approach is vital when discovering how to write a college application essay that shows maturity and intellectual honesty.
Make your sentences slightly less perfect
AI writing tends to be grammatically clean, with evenly sized sentences and repetitive cadence. Human writing has natural variation. So do this: mix short and long sentences, use fragments occasionally for emphasis, ask a question in the middle of a paragraph, interrupt yourself once in a while. Example: “And yes, I know. There are bigger problems. There always are. That’s basically the oldest excuse in the book for not fixing the problem right in front of you.” That kind of cadence feels like a person. Also, avoid the “list of synonyms” problem. AI loves: crucial, essential, significant, vital. Pick one. Or better, write like you talk.
Don’t let robotic prose and predictable rhythms ruin your chances of academic success. Our writers specialize in “voice-matching” to ensure your paper sounds like a high-level student who is deeply engaged with the topic. Order your next opinion essay today and experience the difference that professional, human-led writing makes in your grades.
Don’t over use “research shows” unless you can name the research
A classic AI move is dropping vague authority. “Studies show that…” Which studies? Where? When? Who? If you want to use evidence, do it in a concrete way: name the source, include context, and explain why it matters. Also, a human writer often admits limitations. “I’m not claiming this one study settles it. But it does point to something we keep ignoring.” That kind of line sounds real because it’s cautious in a specific way. If you are developing a formal proposal, knowing how to write a proposal essay will teach you how to cite authority without sounding like a bot.
Give your essay one or two “signature” lines
Opinion essays people remember usually have a couple of lines that feel like they couldn’t have been generated on autopilot. A signature line is slightly surprising, specific, emotionally honest, and easy to quote. Examples: “We keep calling it a productivity problem, but it’s a trust problem.” “The issue isn’t that people don’t care. It’s that caring doesn’t fit into their schedule.” “What we label as ‘laziness’ is often just someone protecting themselves.” If you have one line like that, the essay suddenly feels authored.
Edit like a human, not like a spellchecker
If you only do one thing from this article, do this: edit for voice. Pass 1: Remove filler and repeats. Pass 2: Replace generic phrases with concrete ones. Bad: “People today are more distracted than ever.” Better: “I can’t remember the last time I watched a movie with friends without someone checking their phone during the quiet parts.” Pass 3: Add one personal or specific detail per section. Pass 4: Read it out loud. If you wouldn’t say it out loud, rewrite it. Pass 5: Make sure you actually have an opinion in every paragraph.
If you used AI to help, do this before you submit
Sometimes you do use AI. To outline. To brainstorm. To rephrase a messy sentence. That’s normal. But if you paste AI output and barely touch it, it usually shows. So here’s the clean way to use it: Use AI for ideas, not for the final voice. Write the introduction and conclusion yourself. Rewrite topic sentences in your own words. Insert your own examples and specifics. Remove the “balanced” essay tone and make the stance sharper. Add one paragraph that is purely you—a story, a rant, a confession, a weird observation.
Also, be careful with “perfect” transitions. AI loves them. You don’t need them. Sometimes “And here’s the part that bothers me” is a better transition than “Furthermore”. Write as if someone is going to argue with you in the comments—and then do it anyway. If your teacher or reader disagrees with you, that’s actually a good sign—it means you’ve written something with shape that invites pushback. Make it sharper and more specific; let it have a few rough edges.
How can I tell if an opinion essay is AI-generated?
AI-generated opinion essays often sound confident but lack specific details, over-explain obvious points, use generic examples instead of real ones, avoid taking sharp risks or making bold claims, maintain an evenly paced structure with equal importance to every paragraph, stack transitions like ‘Furthermore’ and ‘Moreover’ mechanically, and tend to repeat the prompt back to the reader in different words. They usually feel neutral and sterile, lacking a genuine human voice or perspective.
What is the biggest mistake people make when writing opinion essays that seem AI-generated?
The biggest mistake is choosing a safe, socially acceptable stance that sounds generic and uncontroversial—like a TED Talk summary. This safe approach results in writing that feels like a brochure: balanced but bland and lacking a real spine. Instead, picking a specific, arguable, somewhat uncomfortable position that you can clearly defend makes your essay more authentic and less AI-like.
How should I start an opinion essay to avoid sounding like AI?
Avoid textbook hooks like ‘In today’s modern world.’ Instead begin with a human entry point such as a tiny personal moment, a blunt statement of your opinion, or a specific observation. These openings create texture and signal a real person is behind the words.
Why should my essay structure avoid perfect symmetry to sound more human?
AI writing loves tidy symmetry—three balanced points with even paragraphs and phrasing. Real opinion writing often has uneven pacing: making a claim, explaining it, going on mini rants, clarifying points, admitting complexities, then landing the conclusion strongly. This uneven shape reflects genuine thinking and helps your essay feel less templated and more alive.
How can I develop a voice in my writing that feels human rather than AI-generated?
Write with clear preferences and quirks—express mild annoyances, humor, rhythm, or personal reactions. Use phrases like ‘I hate when people pretend…’, ‘This sounds dramatic but…’, or ‘Maybe this is just me…’ These elements add personality and make your voice distinct from AI’s neutral tone.
What practical tips help write an opinion essay that doesn’t look AI-generated?
First, pick a clear, arguable stance you care about even if it’s uncomfortable. Start with specific human details instead of generic hooks. Structure your essay unevenly to reflect real thinking rather than neat templates. Use concrete examples instead of generalities. And most importantly, write in a voice full of preferences and personality to show you actually have lived experience and perspective.
With a passion for helping students navigate their educational journey, I strive to create informative and relatable blog content. Whether it’s tackling exam stress, offering career guidance, or sharing effective study techniques
If you’ve ever been told “write an article critique” and your brain immediately went blank, yeah. Same. Because it sounds like you’re supposed to walk into a room, point at someone’s work, and confidently explain what’s wrong with it.
Which is not what a critique is, by the way. A good critique is closer to this: You’re showing that you understand what the author is trying to do, you can evaluate whether it works, and you can back up your opinion with specific evidence from the text. Not vibes. Not “I didn’t like it.” Evidence.
This guide walks you through how to write an article critique, step-by-step, in a way that won’t make you feel like you need a PhD in literature to get started. Many students find that learning how to write an article review provides a solid foundation for mastering these more advanced critical skills.
What an article critique actually is (and what it is not)
An article critique is a structured evaluation of an article’s ideas, arguments, evidence, and overall effectiveness. You’re basically answering: What is this article saying? How is it saying it? Does it do a good job? Where does it fall short, and why?
A critique is not: A summary only (summary is part of it, but not the whole thing), a personal reaction journal entry, a roast, or a line-by-line grammar edit (unless your assignment specifically asks for that).
A critique is also not automatically negative. You can critique something and still think it’s excellent. In fact, strong critiques often include both strengths and weaknesses, because real writing is usually a mix.
Before you start: figure out what kind of article you’re critiquing
This matters more than people think. Critiquing a peer-reviewed research article is different from critiquing an opinion piece in a magazine. A news feature is different from a blog post. They have different goals, and a critique should judge the writing based on the goal.
Quick checks:
Academic research article: thesis, literature, method, results, discussion, citations
Argumentative/opinion article: central claim, logic, persuasive techniques, examples
If you critique a research paper like it’s a personal essay, you’ll end up writing something weird and off-target. So just take 30 seconds and name what you’re looking at.
Struggling to balance complex academic analysis with a tight deadline? Our expert writers deliver custom article critiques that are meticulously researched and professionally formatted. Take the stress out of your semester and get the help you need today.
The basic structure of an article critique (keep it simple)
Most article critiques follow a structure like this:
Introduction (article info + overall evaluation)
Brief summary (main points, not every detail)
Evaluation/analysis (strengths + weaknesses with evidence)
Conclusion (final judgment + what could improve or what it contributes)
Some instructors want headings, some don’t. If you’re not sure, headings usually help clarity. Especially on longer critiques. Now let’s go step-by-step and actually write it.
Step 1: Read the article twice (yes, twice)
First read: understand it like a normal reader. Don’t over-highlight. Just get the flow. Second read: read like a critic. This is where you annotate and look for the bones of the piece.
On the second read, mark: The thesis/central claim (usually in the intro, sometimes later), the main supporting points (topic sentences and section headers help), the evidence used (studies, examples, data, expert quotes, anecdotes), any assumptions the author makes without proving, any moment where you think “Wait, does that follow?” or “That’s a big leap,” and anything that feels especially strong or especially weak.
If you’re short on time and can only do one read, fine, but slow down and do it like the second read. That’s the one that matters for critique. Remember to also consider the specific nature of the article you’re critiquing; for instance how to critique qualitative research might require different focus points compared to other types of articles.
Step 2: Identify the author’s purpose, audience, and context
This is the easiest way to level up your critique fast, because it moves you from “I feel like…” to “The article succeeds/fails because…”
Ask: Purpose: Is the author trying to inform, persuade, analyze, warn, entertain, call to action? Audience: Who is it written for? Experts, general public, students, policymakers? Context: Where is it published, and why does that matter (journal, newspaper, personal blog)? When was it written?
Sometimes a piece is “bad” only because you expected it to do something it never tried to do. Example: An op-ed isn’t supposed to be neutral reporting. A critique should acknowledge that. To sharpen your ability to dissect these elements, you might explore how to write a critical analysis essay for more in-depth strategies.
Step 3: Write a one-sentence thesis for your critique
Yes, your critique needs a central point too. Before you write anything else, create one sentence that captures your overall evaluation. Use a simple template:
“The article effectively argues [X] by [Y], but it is limited by [Z].”
“While the article provides a clear overview of [X], its argument is weakened by [Y].”
“The author’s main claim that [X] is compelling because [Y]; however, [Z] reduces the article’s credibility.”
This sentence becomes the anchor for your whole critique. If you ever get lost mid-draft (you will), come back to this.
Our academic specialists understand exactly how to construct a high-level critique that satisfies even the toughest professors. We offer bespoke writing services tailored to your specific subject matter and grading criteria. Secure your academic success by ordering a custom-written critique now.
Step 4: Draft the introduction (don’t overthink it)
Your intro should do three things: Name the article (title, author, publication, date if you have it), state the topic and what the article is trying to do, and give your overall evaluation (your critique thesis). That’s it.
A clean intro template: In “[Title]”, [Author] argues that [X]. Published in [Source] in [Year], the article aims to [purpose]. Overall, the article is [effective/partially effective/ineffective] because [reason]. Don’t make it dramatic. Don’t write a life story. Just set the stage.
Step 5: Summarize the article briefly (you’re proving you understood it)
This is where a lot of critiques go wrong. People either summarize for 4 paragraphs and forget to critique, or don’t summarize at all and jump into opinions with no context.
Your summary should be a short, controlled recap of the author’s main points. A good summary includes: the thesis/central claim, 2 to 4 main supporting ideas, and the type of evidence used (not every example, just the categories). Keep it tight. Usually one paragraph, sometimes two if the article is dense.
One trick that helps: imagine you’re explaining the article to a friend who didn’t read it. What would you say in 30 seconds? That’s the summary you want.
Step 6: Start the critique section with strengths (it makes your critique feel fair)
Even if you hated the article, there’s almost always something you can credit: clarity, organization, an interesting topic, a strong example, a useful framework. Also, mentioning strengths up front makes your criticism sound more thoughtful and less like you came in swinging.
Common strengths to look for: Clarity and organization (Does the article have a clear thesis? Are the sections logically ordered?), Quality of evidence (Are claims supported with credible sources? Are statistics current?), Depth and insight, and Tone and audience fit. When you write strengths, do not keep it vague. Support them with examples from the text.
Step 7: Critique weaknesses, but do it with specific evidence (this is the heart of it)
This is where you earn your grade. Weaknesses can come from a lot of places. Common ones include a weak or unclear thesis, gaps in logic (where conclusions don’t follow the evidence), evidence problems (outdated, thin, irrelevant, or misinterpreted), bias, and methodological limitations (for research articles). For those tackling complex theoretical texts, reviewing how to write a philosophy paper can help in identifying nuanced logical fallacies.
If you aren’t sure, phrase it cautiously: “The study appears limited by…” rather than “This is invalid.” This is not about nitpicking grammar; it’s about moments where the writing damages the argument, such as vague language or emotional language that replaces evidence.
Don’t let a difficult assignment compromise your GPA when professional help is just a click away. Our writers are experts at identifying deep-seated logical flaws and articulating strengths with precision. Join thousands of successful students and get your critique written by a pro today.
Step 8: Use the “claim, evidence, explanation” pattern for every critique point
This is the most reliable way to write critique paragraphs that sound mature and convincing. For each point you make, follow this mini-structure:
Claim: What are you criticizing or praising?
Evidence: What part of the article shows this? (quote or paraphrase)
Explanation: Why does it matter? How does it affect the argument?
Example: Claim: The article relies heavily on anecdotal evidence. Evidence: The author’s main support comes from personal stories in paragraphs 4 to 6. Explanation: This limits credibility because anecdotes can’t show whether a trend is widespread. This is how you avoid sounding like you’re just complaining.
Step 9: Bring in outside sources only if you’re supposed to
Some critiques are “closed book.” You can only use the article itself. Other critiques require you to evaluate accuracy using outside research. If your assignment allows outside sources, use them carefully. You don’t need ten citations. You need one or two strong ones that directly challenge or support a key claim. Don’t use sources to show off; use them when they genuinely clarify whether the article holds up.
Step 10: Write the conclusion (final evaluation, not a repeat)
Your conclusion should answer: What is your overall judgment? Who would benefit from reading the article? What should be improved, or what does it contribute? Keep it short. You’re not introducing new critique points here. You’re tying it together. Overall, the article succeeds in [X], particularly through [Y]. However, its effectiveness is weakened by [Z]. With stronger [evidence/focus/logic], the article would provide a more reliable contribution.
Common mistakes (that quietly wreck critiques)
Being too summary-heavy: If you’re just recapping what the author says, you’re not evaluating. After the summary, use words like “however,” “this suggests,” or “this fails to address.”
Making big judgments with no text evidence: Show how the author is biased by quoting the framing or pointing to missing counterarguments.
Confusing disagreement with critique: Critique the writing and reasoning, not just whether it matches your opinion.
Attacking the author instead of the article: Keep it professional. Use “The article does not address…” rather than “The author is ignorant.”
Critiquing the wrong criteria: Judge it by what it is. Don’t criticize a short news piece for not being a full academic study.
Quick checklist before you submit
Did I clearly state the article’s thesis in my summary?
Did I include my own overall evaluation in the introduction?
Did I discuss both strengths and weaknesses?
Did every critique point include evidence from the article?
Did I explain why each point matters?
Did I avoid turning it into just a personal opinion rant?
Final note: Writing an article critique gets easier the moment you stop trying to sound like a critic and start acting like a careful reader who can justify their reactions. Read closely. Quote selectively. Explain your reasoning. Be fair. And make sure your critique has a spine—one clear overall judgment that holds the whole thing together.
Frequently Asked Questions
What is an article critique and how does it differ from a summary?
An article critique is a structured evaluation of an article’s ideas, arguments, evidence, and overall effectiveness. Unlike a summary, which only outlines the main points, a critique assesses how well the article achieves its purpose by analyzing strengths and weaknesses with specific evidence from the text.
Is an article critique always negative?
No, an article critique is not automatically negative. It involves evaluating both strengths and weaknesses of the article. A strong critique acknowledges what works well and what falls short, providing a balanced and evidence-based assessment rather than just personal opinions or dislikes.
How should I approach critiquing different types of articles?
Before starting your critique, identify the type of article you’re reviewing—such as academic research, opinion piece, news article, or informative content. Each has different goals and criteria. For example, academic articles focus on thesis, methodology, and results; opinion pieces emphasize central claims and persuasive techniques; news articles require balance and factual reporting. Tailor your evaluation accordingly.
What is the basic structure to follow when writing an article critique?
Most critiques follow this simple structure: 1) Introduction with article information and overall evaluation; 2) Brief summary highlighting main points; 3) Evaluation/analysis detailing strengths and weaknesses supported by evidence; 4) Conclusion offering final judgment and suggestions for improvement or contribution to the field.
How many times should I read the article before writing my critique?
It’s recommended to read the article twice. The first read is to understand it like a normal reader without over-highlighting. The second read is critical: annotate key elements like thesis, supporting points, evidence, assumptions, logical leaps, and note particularly strong or weak sections. This careful analysis forms the basis for your critique.
Why is it important to identify the author’s purpose, audience, and context in an article critique?
Understanding the author’s purpose (informing, persuading, entertaining), intended audience (experts, general public), and context (publication venue and timing) helps you evaluate whether the article succeeds in its goals. This shifts your critique from subjective impressions to objective analysis based on what the author aimed to achieve.
With a passion for helping students navigate their educational journey, I strive to create informative and relatable blog content. Whether it’s tackling exam stress, offering career guidance, or sharing effective study techniques
Theories of Poverty and Paths to Eradication – Essay Freelance Writers
1
The Theories of Poverty and Paths to Eradication
Introduction
Poverty is perhaps one of the World most common problems. Poverty is described as the general lack of basic necessities, such as food, Medical care, safety, housing, and shelter. Poverty is categorized into to two kinds, Absolute, and Relative poverty. Absolute poverty is that kind that is characterized by a severe lack of necessities (United Nations, 1995). This kind of poverty usually varies from one person to another and is primarily dependent on the income capacity of an individual.
According to a 2004 Joint Report on Social Inclusion, the European Commission explained that relative poverty is when an individual is living with inadequate income and human needs resources. Such individuals are usually a little more disadvantaged through employment, inadequate health care, sport, and recreation. They are most of the times marginalized socially, culturally and economically. Relative poverty, on the other hand, is usually measured by the level of individual society lives. It is mainly caused by lack of the means of sustainable livelihoods, lack of access to education. It is possible to eradicate it because most of the individuals suffering from this kind of poverty usually lack the support to improve their lives (United Nations, 1995). In the recent years, the primary priority of most Countries has been on poverty reduction and eradication. This paper shall focus on understanding the theories of poverty and the different solutions they provide to eradicate poverty.
Struggling with Complex Sociology or Economics Assignments?
Our team of professional academic writers specializes in development studies, economic theory, and social policy research. We provide original, deeply researched papers that reflect the highest academic standards and current global data. Click here to collaborate with a subject matter expert and secure your top grade today.
The following terms will from time to time be used in throughout this paper. Poverty trap: A situation where poverty tends to increase due to efforts of the poor person, such as refusal to access free public education, refusal to receive free vaccination and refusal to participate in voting. Poverty line: This is the set minimum level of income that is said to be inadequate in a particular country. The poverty line is set at $1.25 and $2.
Historical Definitions of Poverty
The definition of poverty has changed over the years. In the previous years, poverty was measured with the parameter of basic needs. Adam Smith, for instance, defined poverty as the inability to purchase basic needs required by nature. Smith further explains the kinds of necessities a person requires, a combination of relative and absolute needs (Smith, 1776).
Joseph Rowntree defines poverty by distinguishing it from to two, primary and secondary poverty. According to Rowntree, primary poverty is the lack of or insufficiency to obtain necessities for the maintenance of physical sufficiency (Rowntree, 1901). Rowntree goes ahead to explain that individual suffering from secondary poverty are above the poverty line and are not objectively poor.
3
A famous Economist Karl Max, states that poverty originates from the needs, expectations and enjoyment from the society. It is the society that measures them and dictates whether or not a person is poor. Most of the thresholds for measuring poverty are of social nature (Wood, 1988).
Contemporary Definition of Poverty
As mentioned earlier the parameters for measuring and defining poverty are quickly changing. This is mainly due to the changing understanding of the word poverty. These new definitions are determined by the level of education, population, gender issues just to mention a few. Amartya Sen has been in the forefront in the contribution to the poverty issue. His definition differs from most of the historical definitions. He, for instance, critics the division of poverty into relative and absolute poverty. According to him, stating that absolute poverty relates to the lack of income, commodities and resources is a narrow and fixated thinking.
How to Get Expert Writing Help Fast
Simply submit your detailed instructions through our secure portal to receive an instant custom quote for your project. You will be matched with a specialized writer who will handle your research and drafting with absolute precision. Your finalized, high-quality document will be delivered directly to your dashboard for immediate download and review.
Peter Townsend says that poverty is the lack of resources necessary to allow participation in the activities, customs, and way of life approved by the society. He adds that individuals can access resources depending on the different systems set by the government for them. He says that poverty is mainly characterized by the exclusion effect it carries. Exclusion from the ordinary patterns of living is what cause poverty.
Several intuitions have also played a role in defining poverty, for instance, the World Bank, states that poverty levels are measured by the income and consumption levels. Therefore, an individual is said to be poor if their income or consumption level falls below the minimum level necessary to meet the basic needs. It is this minimum level that is mainly referred to as the poverty line. The minimum poverty line level is currently at $1.25 and $2 per day. Further, the World Bank recognizes that poverty definition could vary from country to country and that poverty is the general deprivation in well-being. For example, it may include lack of food, low income, and lack of access to basic services necessary for survival. In some instances poverty includes lack of access to health care facilities, lack of education, poor access to clean water and sanitation, inadequate security, lack of political voice, and lack of opportunities for better life.
5
The Copenhagen Declaration by the United Nations published in 1995 incorporates the definition of poverty from both the developing and developed country point of view. In the Summit an agreement was reached on the definition of poverty to include, the lack of income and productive resources for sustainable livelihoods, Hunger and malnutrition, bad health, limited or lack of access to education. It would also include, homelessness, lack of security, morbidity and mortality, lack of participation in decision-making in both civil and cultural spheres of life. During the Summit, it was recognized that although poverty occurs in all countries it is very common in developing countries. Developed countries are mostly coupled with pockets of poverty (United Nations, 1995).
The above definition is not different from the United Nations public statement issued in 1998, defines poverty as the denial of choices and opportunities. The statement categorically states that poverty is a violation of fundamental human dignity. Poverty means the lack of participation in the society; lack of basic necessities such as food, clothing and education, Poverty also means not having land to grow food on, lack of employment, not being able to access credit and the lack of security. Poverty causes marginalization and living in fragile environments with no clean water and sanitation (United Nations, 1998).
6
THEORIES OF POVERTY
Like the different definitions of poverty, there exist different theories of poverty. All this theories explain the main cause of poverty. These theories include the classical theory, the neoclassical theory, the Liberal or Keynesian theory, and the Marxist theory. All this theories adopt a different approach to the cause of poverty and the way Poverty can be eradicated. This section shall focus on all these theories in detail.
1. Classical Theory.
Classical theory was developed during the 18th and 19th Century by the classical economists. The main Classical economists are Adam Smith and David Ricardo. The classical economists were of the opinion that every individual is responsible for their destiny and at the same time the choice of being poor or rich. This theory is divided into the theory of value and distribution. For instance, it is assumed that the sale of a product is equal to the cost of production of that particular product and that the cost of a product is equal to its distribution level.
Empower Your Academic Journey Today
High-quality research on global issues like poverty requires a deep understanding of multi-disciplinary theoretical frameworks. Our experts help you articulate these complex ideas clearly and persuasively in every assignment. Click here to start your order and take the next step toward your professional goals.
As a result, poverty is a choice made by an individual, for instance, lack of proper budgeting skills, lack of control, and therefore, these individuals are poor because of their decisions. When the State intervenes to help such individuals, it makes them even lazier therefore guaranteeing them as economic inefficiency. Under this theory income generating projects that are skewed between poor individuals and society as a whole, welfare programs are the reason for absolute poverty. The government is, at most, justified to intervene whenever poor people need supportive activities or threats to correct for perverse economic incentives. A large majority of the policy prescriptions under this view focus on efforts to raise the productivity of deprived individuals for them to join the labor force as soon as possible.
One controversial theory from the classical theory is the subculture of poverty theory. This approach suggests that poverty is usually passed from one generation to another due to genetic upbringing. This child brought up in a poor family will likely be poor because the only role models this child associates with are his or her poor parents. Oscar Lewis suggests that poor members of the society usually display a similar characteristic and therefore poverty becomes a way of life passed down from one generation to another (Lewis, 1965).
8
Another Approach to the classical theory is behavioral or also known as the decision-based theory. It suggests that the well-being of individuals is determined by their economic decisions. Therefore, poor people are responsible for their poverty. The individual characteristics vary from the lack of hard work, work ethics, low levels of education (Rank et al, 2003). The state has no role in intervening since individual behavior and decisions are the cause of poverty.
2. Neoclassical Theory
Unlike the Classical theory of poverty, the neoclassical theory recognizes the reasons for poverty that are beyond an individual’s control. It recognizes factors such as lack of economic power, market failures, private assets, illiteracy, bad health, age; lack of employment as the main cause of poverty that are beyond an individual’s control. Therefore, poor persons are not necessarily responsible for their poor status. In his publication, Alfred Marshall invented and explained the neoclassical theory. Marshal explained price by the intersection of supply and demand curves. He took supply and demand as stable functions and extended supply and demand explanations of prices to all time horizons. He argued supply was easier to vary over longer time horizons, and hence became a more important price determinant in the very long run. The classical theory recognizes that individuals have different talents, skills and capital that determine if they are poor or not. Market failures, economic changes can also cause poverty (Davis, 2007).
9
The classical theory can take several approaches. The first is the assets and financial approach. When there is no income diversification due to the holding of very few assets, then this is likely to affect the chances of being poor and the period of being poor. This is mostly common if there is no job security (Ulimwengu, 2008). Poor people are characterized by not having bank accounts and likely not to develop a saving culture. Thus, poverty can only be eradicated I f the poor learn to save. This will in return benefit them by access to credit facilities.
The second approach is incentives, market failures and access to credit. Despite being poor, most poor people seem to make decisions that make them even poorer. The main reason for this is because the poor have limited resources are likely to trade these resources to access basic needs. The human capital approach suggests that economic development lies in market completion and market equilibrium. The neoclassical theory primarily focuses on individuals choices versus their education and training. Lyndal (1968) explains that it is education, intelligence and environment that determine the distribution of personal earnings. Lack of or under-investing in education is a characteristic a poorest household (Machin, 2009).
10
3. Keynesian theory of Poverty.
It is also known as the Liberal theory of poverty. This theory looks at different factors that cause poverty. It looks at economic growth as the possible way of reducing poverty. The theory justifies the reason the government should intervene at the Macro economical level through the monetary empowerment to help solve the unemployment problem. In this theory lack of employment is viewed as the main source of poverty and thus most solutions should be targeted at solving the unemployment problem. It further suggests that the main signs of poverty are usually, poor levels of human capital, lack of infrastructure.
Keynens, the pioneers of the Keynesian theory, believes that development of market forces is likely to promote economic development. The Keynesian theory embraces the importance of education in the eradication of poverty. Keynes insists on the government investment in public education as a means of increasing human capital aggregate. This is where the role of the government in the eradication of poverty comes in since the intervention of the government is needed to several issues to enhance economic growth and poverty reduction. This is contrary to the classical theory that does not favor government intervention.
11
The poor are mainly viewed as the small part of a population that are unemployed or cannot work although they wish to work. The theory recognizes hat poverty can be as a result of market failures due to harsh economic times. There exist a relationship between poverty and the rate of employment. For instance, the normal explanation would be that, if a person is not employed then he or she is likely to be poor. Therefore, poverty is amplified by unemployment. If the pay received in employment is not sustainable, then they will be poor. It is for this reason that the Keynesian theory insist on the steadiness of employment. This steadiness will lead to a saving culture and hence poverty reduction. Therefore, employment is said to influence the transformation of assets into entitlements (Sen, 1983).
Unemployment is caused by several factors, such as inflation, asset market bubbles, and high foreign debt. When the rate of inflation is high, then the rate of unemployment is likely to increase. High inflation rates cause high cost in production. With the high cost, employers will likely cut down on the number of employees or the wages and salaries. High inflation rates also increase the prices of basic commodities. Inflation rate increase always increases the rate of poverty (Agenor, 1999). A very high foreign debt places a burden on taxpayers and is likely to lead to unemployment.
12
4. Marxist theory of Poverty
It is also known as the radical theory of poverty. This unlike the Keynesian theory states that economic growth is insufficient to reduce poverty. This is because the poor people themselves do not benefit or benefit minimally from economic growth. The Marxist theory also places emphasis on class rather personal and individual characteristics and capabilities. This theory was developed by Karl Max. Max states that due to the high unemployment rate, employers reduce the minimal wage and, therefore, the poor still remain poor. He, therefore, explains that adequacy in employment is the main ingredient or the eradication of poverty. Discriminative laws that divide people into classes are also another cause of poverty. Simple and adverse actions such as the pollution of the environment, for example, makes the poor suffer more.
On discrimination a class, Marx say as that social and political divisions deny poor people from accessing essential facilities such healthcare, and education. Discrimination involuntarily isolates certain individuals from particular levels in the society. This discrimination goes to the extent of the lack of access to economic resources. Therefore, economic growth is not a solution to poverty. Poverty can only be solved through the enactment of anti-discriminatory laws, coupled with even economic development (Jung and Smith, 2007). The poor are also not adequately represented in the political sphere; most the representation positions are occupied by the rich, and therefore it is hard to advocate for the interest of the poor.
13
Conclusion
Poverty is the lack of or the deprivation of the basic human needs such as food, shelter, clothing, education and security. This definition has changed over times to include real-time issues faced by the poor. Poverty levels vary from one country to another. Developing countries, however, have high poverty levels with the developed faced with a smaller percentage of poverty levels. Several theories have been developed to define, explain the causes and solutions to poverty.
The Classical theory is of the view that poor individuals handle being poor. This is because they have a choice to be poor or rich, and it is by their poor decisions that they are poor. The theory advocates that the government should not interfere in helping poor people and that they should be left to help themselves. The Neoclassical theory looks at the causes of poverty that are beyond an individual’s control. The theory suggests that poverty can be as a result of factors, such as lack of access to education, lack of capital, lack of employment, factors that are beyond the control of a person. The theory suggests that the government should interfere minimally to help these poor people be productive again. Another theory is the Keynesian theory, which blames unemployment as the main cause of poverty. It suggests that if people are unemployed then they will likely be poor. The government, therefore, has the responsibility of guaranteeing employment to eradicate poverty since the poor themselves do not benefit. The last theory is the Marxists theory, which states that economic growth is not the solution to poverty. It, however, suggests that enactment of anti-discriminatory laws is highly likely to reduce poverty.
Why Essay Freelance Writers is Your Best Choice
We prioritize your academic success by offering 24/7 support and free unlimited revisions on every order. Our platform guarantees 100% plagiarism-free work backed by rigorous quality control checks. Join thousands of satisfied students who trust us for reliable and expert academic assistance on complex economic topics.
Agenor, PR, (2002), “Macroeconomic Adjustment and the Poor: Analytical Issues and CrossCountry Evidence”, World Bank Working Paper No.: 2788, World Bank:Washington, DC.
Davis E P (2004), “Is there a pensions crisis in the UK?”, Geneva Papers on Risk and Insurance, 2004/3, 343-370.
European Commission (2004), “Joint report by the Commission and the Council on social inclusion”,EC, Brussels.
Jung,S. Y., andSmith, R. (2007),”The economics of poverty: Explanatory theories to inform practice”, Journal of Human Behavior in the Social Environment,16(1-2), 21-39
Lewis O (1965), “The children of Sanchez”, Penguin, Harmondsworth.
Lydall, H., (1968) “The Structure of Earnings”, Oxford University Press,Oxford.
Machin S (2009), “Education and inequality” in eds. W Salverda, B Nolan and T M Smeeding, “The Oxford Handbook of Economic Inequality”, Oxford UniversityPress
Rank, M. R. (2001), “The effects of poverty on America’s families:Assessing our research knowledge”, Journal of Family Issues, 22: 882-903
Rowntree B S (1901),“Poverty, a study of town life”, MacMillan, London.
Sachs, J. (2005), “The End of Poverty”, London: Penguin
Sen, A. (1983), “Poor, relatively speaking”, Oxford Economic Papers,35, 153-169
Smith, A. (1776), “An enquiry into the nature and causes of the wealth of nations”, London: Methuen & Co., Ltd
Ulimwengu, J. (2008), “Persistent poverty and Welfare Programs in the United States”, IFPRI Discussion Paper 00818.
United Nations (1995),” The Copenhagen Declaration and Programme of Action”, World Summit for Social Development, New York, United Nations
United Nations (2013),“Human Development Report 2013”, New York, United Nations.
Townsend, P. (1979),”Poverty in the United Kingdom”, London, Allen Lane and Penguin Books. Print.
Wood, J, C. (1988), “Karl Marx’s Economics: Critical Assessments”, Croom Helm Ltd., London.
With a passion for helping students navigate their educational journey, I strive to create informative and relatable blog content. Whether it’s tackling exam stress, offering career guidance, or sharing effective study techniques
This website uses cookies to improve your experience. We'll assume you're ok with this, but you can opt-out if you wish. ACCEPTPrivacy Policy
Privacy & Cookies Policy
Privacy Overview
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. This category only includes cookies that ensures basic functionalities and security features of the website. These cookies do not store any personal information.
Any cookies that may not be particularly necessary for the website to function and is used specifically to collect user personal data via analytics, ads, other embedded contents are termed as non-necessary cookies. It is mandatory to procure user consent prior to running these cookies on your website.